
Overnight Summary and Early Morning Trading: Wednesday and Thursday are limited versions due to travel. Friday will be normal production.
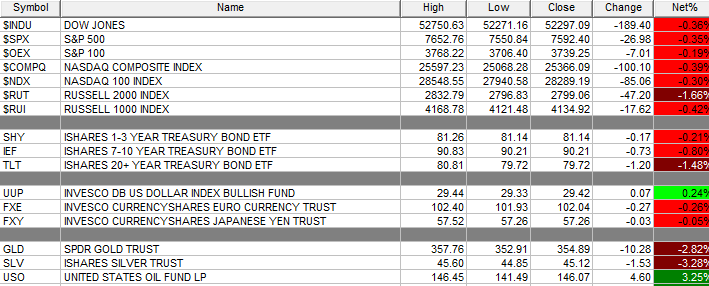
- The S&P 500 finished Thursday lower by -0.35% at 7592.40 from Wednesday higher by 1.31% at 7619.38.
- The S&P 500 sees support now at 7500 from 7600. Resistance is now at 7600 from 7700. In the last six months, support has moved from 6300 to 7600.
- The QQQ (Nasdaq-100 Index ETF) sees support now at 680 from 690. Resistance is now at 690 from 700 as the QQQ closed higher at 688.17 from 690.38
- Bond Market is at 5.129% from 4.99%.
Executive Summary:
- Bond Market have had yields below 5.00% from recent highs and closed last week at 4.864% from 4.933% the week before.
- Stocks moved into a four-week losing streak with the S&P 500 falling last week, ended 11/06 by -2.68%.
- U.S. moves into Week 40 of its attack on Iran, eight months.
- The S&P 500 lost -1% on four days last month. We clustered on the downside in October and now can do it again in November with a second down day of more than -1%.
Key Geopolitical Events of Note
-
Economic news of note.
-
Weekly- Baker Hughes Rig Count of note.
- Monthly- PPI of note.
-
-
President Trump’s Schedule:
- Participates in Executive Time at 8:00 a.m. EDT.
- Participates in a Policy Meeting at 12:30 p.m. EDT.
- Participates in a Policy Meetings at 3:00 p.m. EDT, 4:00 p.m. EDT and 4:30 p.m. EDT.
- Fed and Other Speakers of Note: Bowman (10:50 a.m. EDT), Daly (12:00 p.m. EDT), Jefferson (7:30 p.m. EDT)
Capital Raises Announced After The Close:
- IPO Filings & News: Barrick (B) files S-1 for proposed American Barrick IPO; NYSE listing planned under ABGC.
- Notes Files: None of note.
- Secondaries Filed Or Priced:
- CTRE pricing of common stock.
- EQ: Form S-3.. 35,087,717 Shares of Common Stock.
- KDP – Pricing of Public Offering of Common Stock.
- KLXE: Form S-3.. 59,416,400 shares of Common Stock.
- NSPR – Proposed Public Offering.
- PRME – Closing of Public Offering and Full Exercise of the Underwriters’ Option to Purchase Additional Shares.
- RZLT – Pricing of Approximately $100 Million Underwritten Offering of Common Stock and Pre-Funded Warrants.
- SO – pricing of equity units.
- VIR Proposed Public Offering.
- Convertible Offerings Filed or Priced:
- GH proposes $500 million convertible senior notes offering due 2032.
- EPR prices $500 million convertible notes.
- KITT: Form S-1.. 10.00% Series E Convertible Preferred Stock.
- Private Placement: None of note.
- Direct Offering: None of note.
- Selling Shareholders:
- FORM files for 2,234,887 share common stock offering by selling stockholder.
- KLXE files for 59,416,400 share common stock offering by selling stockholders.
- LSTA: Form S-3.. 350,498,987 Shares Common Stock Offered by the Selling Stockholders.
-
Mixed Shelf Offerings:
- VYLR files mixed securities shelf offering.
- VIR Form S-3ASR Mixed Shelf Offering.
- AIRO files for $100 million mixed securities shelf offering.
- TLPH Form S-3..$150,000,000 Mixed Shelf.
- After The Close:
-
Earnings After The Close:
-
-
Beat: GEMI +0.12, AMAT +0.10, CSCO +0.07, HTFL +0.07, LFMD +0.03, DLO +0.02 of note.
- Missed: ARWR (3.59), ANDG (1.64), CBRS (0.52), FLO (0.05), KLC (0.03), OFRM (0.01)of note.
-
- Inline: None of note.
-
-
Dividend Ex Update:
- Friday: SHEL: $0.78 | SCHW: $0.32 | UL: $0.52 | SBUX: $0.63 | PH: $2.00 | GLW: $0.28 | GSK: $0.45 | DUK: $1.08 | CTAS: $0.52 | SHW: $0.80 | HON: $0.70 | CRH: $0.39 | TFC: $0.52 | STRC: $0.03 | HONA: $0.40 | MSCI: $2.05 | MT: $0.15 | RPRX: $0.23 | WEC: $0.95 | CTSH: $0.33 | OTIS: $0.44 | CHD: $0.31 | SW: $0.45 | PAG: $1.46 | SJM: $1.12 | DOC: $0.10 | IVZ: $0.21 | AIT: $0.51 | BPOP: $0.90 | FCFS: $0.46 | FSS: $0.15 | AUB: $0.40 | STNG: $0.75 | WING: $0.33 | MMS: $0.33 | PFS: $0.24
- Monday: XOM: $1.07 | KLAC: $0.23 | COP: $0.93 | COF: $0.80 | SO: $0.76 | EQNR: $0.39 | UPS: $1.64 | CEG: $0.43 | STRC: $0.03 | ROK: $1.45 | KR: $0.39 | UI: $1.00 | HSY:$1.45 | JBL: $0.08 | IP: $0.46 | GEN: $0.13 | CF: $0.60 | PAAS: $0.19 | CG: $0.35 | CNA: $0.48 | AFG: $3.50 | UDR: $0.14 | JEF: $0.40 | TX: $0.90 | WYNN: $0.25 | OSK: $0.57 | AGCO: $0.30 | AG: $0.01 | SWX: $0.65 | TFX: $0.34 | SIGI: $0.48
- SR increases annual stock dividend to $3.46 per share from $3.30 per share, bringing quarterly rate to $0.865. an increase of 4.8%
-
News Of Note:
- Celanese (CE) closed the sale of an additional 19% interest in the Nutrinova food ingredients joint venture to Mitsui, generating total cash proceeds of $152 million.
- Applied Materials (AMAT)beat on revenues and earnings for Q4 and guidance beats for Q1 .
- Cisco (CSCO) beat on revenues and earnings for Q1 and guidance beats for Q2.
- Cerebras (CBRS) prelim Q3 ($0.67), may not be comparable to the ($0.15) FactSet Consensus; revs $230.9 million vs $214.70 million FactSet Consensus. Expects to triple revenue in 2027.
- Anthropic’s IPO is roughly 6x oversubscribed.
- Price Changes:
- Pops: CBRS +18.0%, GEMI +3.4%, FPS +2.0% higher.
- Drops: KLC -21.3%, FLO -8.0%, OFRM -6.0%, DLO -2.6%, ANDG -2.2% lower.
-
Executive Changes:
- Buyback
- MAX repurchases 1.13M shares in $16 million private buyback from White Mountains affiliate.
- JBSS authorizes share repurchase program of up to $20 million of common stock and declares special cash dividend of $2.00/share
What’s Happening This Morning:
Futures S&P 500 +23, NASDAQ +67 and Dow Jones +95. Europe is lower ex FTSE and Asia is lower ex Japan. Bond yield is at 5.135% from 5.004% on the 10-Year. Crude Oil and Brent Crude are mixed with Natural Gas higher. Gold higher with Silver and Copper lower. The U.S. Dollar is higher versus the Euro, higher against the Pound and higher against the Yen. Bitcoin is at $69,222 from $73,894.
Sector Action: 2 sectors higher and 16 lower.
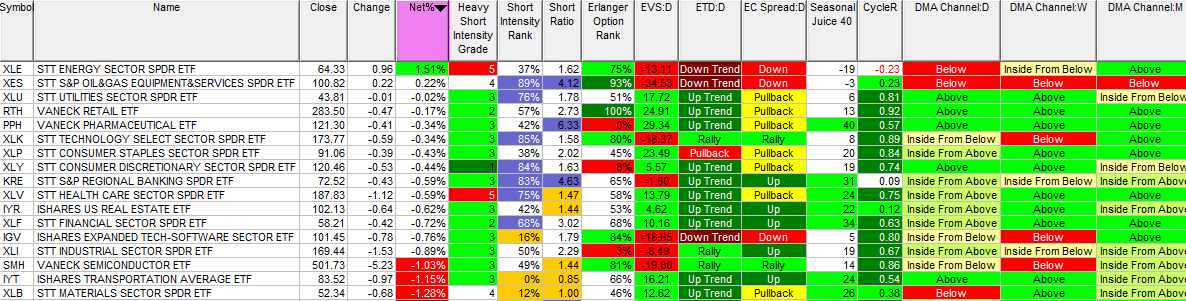
- One-Month Winners: Technology, Utilities, Consumer Cyclical, Consumer Defensive and Communication Services of note.
- Three-Month Winners: Energy, Technology, Materials, Healthcare and Communication Services of note.
- Six-Month Winners: Technology, Energy, Financials, Healthcare and Consumer Defensive of note.
- Twelve-Month Winners: Energy, Technology, Materials, Industrials, Financials and Communication Services of note.
- Year-to-Date Winners: Energy, Technology, Materials, Industrials, Financials and Healthcare of note.
Upcoming Earnings Of Note: (Erlanger Chartroom Software – sorted by market cap, highest to lowest with most visible names)
- Friday After the Close:
- Monday Before the Open:

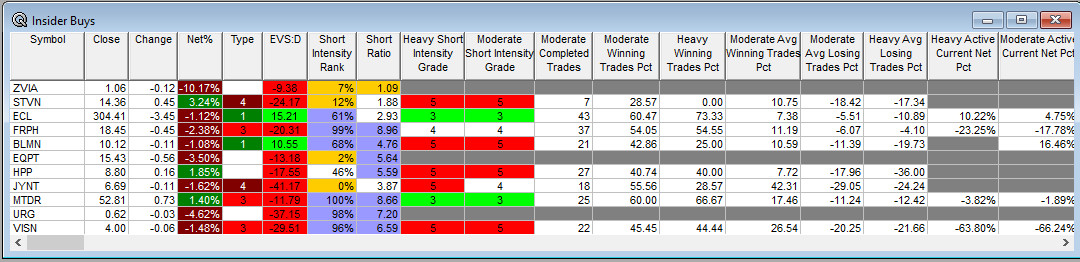
Insider Activity: ECL FRPH MTDR see Insider Buying with dumb short selling. BLMN HPP JYNT VISN sees Insider Buying with smart short sellers. Above $100,000 in purchases with high shorts but no history: URG of note.
Notable Earnings of Note This Morning:
- Beat: None of note.
- Missed: None of note.
- Flat: None of note.
- Still to Report: RMIX of note.
Company Earnings Guidance:
- Positive Guidance: TWST, MWH, LGN of note
- Mixed: REZI, TDG of note.
- Negative or Mixed Guidance: ADIG of note.
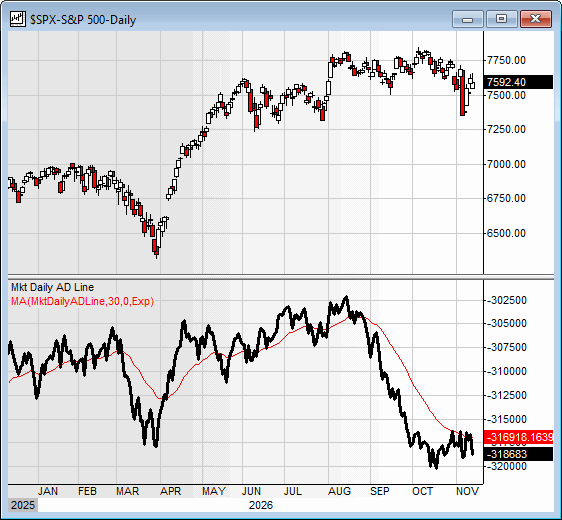
Advance/Decline Line Chart: Still trying to find a meaningful bottom.
Economic & Geopolitical
- Federal Reserve Speakers Schedule: (see above).
-
President Trump’s Schedule: (see above)
Economic Data Due Out
-
- Weekly –
- Baker Hughes Rig Count is due out at 1:00 p.m. EDT.
- Monthly
- October PPI is due out at 8:30 a.m. EDT and expected to fall to 0.40% from 1.30%.
- Weekly –
M&A Activity & Daily: None of note.
Pre-Market Changes:
- Pre-Market Gainers: CBRS +17.1%, LFMD +12.7%, AFYA +12.3%, RZLT +11.9%, NU +4.0%, VSAT +3.8%, ALM +2.9%, FINW +2.8%, GEMI +2.7%, NVDA +2.6%, SMFG +2.6%, PRME +2.3%, QXO +2.3%, BKD +2.1%, ELVN +2.1%.
- Pre-Market Decliners: KLC -15.6%, VIR -12.7%, FLO -9.2%, ANDG -8.3%, AZUL -8.0%, OFRM -7.6%, ENHA -5.8%, KLXE -5.2%, PRAX -3.7%, DLO -3.3%, CSCO -3.1%, FTW -2.6%, GLXY -2.0%, AMD -2.0%.
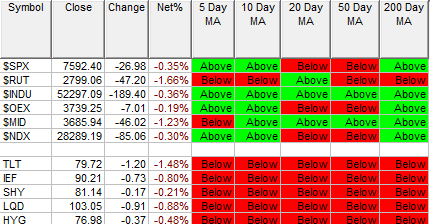
Moving Average Stats: 63% from 80% of stocks are positive with 0% from 28% of bonds are positive.
Rags & Mags:
- Former Nvidia CEO Belittled His Replacement Calling Her a “Deer in Headlights”. (WSJ)
- Before stepping down amid escalating scandal over multiple undisclosed affairs, former Nvidia (NVDA) CEO Jensen Huang openly dismissed interim CEO and longtime CFO Colette Kress—telling executives in a meeting that she looked like a “deer in the headlights” and was merely a “reporting CFO” unsuited for strategic leadership. Now tasked with stabilizing the AI chipmaker after a massive market-cap wipeout, Kress takes the helm despite never having been groomed for the top job, though she previously earned credit internally for scaling back Nvidia’s financial exposure to a massive $300 billion OpenAI data-center deal.
- Microsoft Races to Fix Outages with Outlook In One of Its Longest Outages. (Bloomberg)
- Microsoft (MSFT) engineers worked overnight to contain a massive global service disruption that knocked Outlook, Teams, SharePoint, and Copilot offline for roughly 17 hours across 74 countries—sending MSFT shares down nearly 3% in pre-market trading. Attributed to an elevated infrastructure load triggered by servers becoming unexpectedly unavailable rather than a cyberattack, the prolonged breakdown forced emergency workarounds across major institutions, including Euronext asking listed firms to phone in disclosures and hospitals declaring internal communications alerts.
- Widespread Microsoft Outage Continues. (CNBC)
- Service disruptions across Exchange Online and Microsoft 365 dragged into a second day on Friday morning after initial overnight remediation patches failed to stabilize remaining servers. While Microsoft (MSFT) reported incremental recovery across several workloads by early Friday, queued email delivery delays of up to 48 hours persisted for enterprise and government users worldwide, including the U.S. House of Representatives, the UK’s National Health Service, and Japanese and Australian agencies.
- Commerce Secretary Lutnick Took a Softer Line on Nvidia As Calls For Tougher Controls Grew. (NYT)
- Commerce Secretary Howard Lutnick resisted internal White House pushes to tighten export curbs on advanced AI compute access for Chinese firms—even after Oracle (ORCL) agreed to scrap a $7 billion Southeast Asian chip-leasing deal with Tencent and tech leaders urged stricter enforcement. Arguing that broader restrictions on remote chip access would escalate a trade war with Beijing, Lutnick’s softer posture—alongside reports that Commerce halted a smuggling probe into an NVDA customer—has drawn sharp congressional scrutiny and document preservation demands ahead of upcoming Senate hearings.
- Market Wrap: Stocks Gain as Fed Bets Face Fresh Inflation Test. (Bloomberg)
- U.S. equity futures edged higher in early Friday trading as traders balanced ongoing AI sector rotation—which has lifted chip rivals AMD and AVGO while pressuring NVDA and MSFT—against upcoming inflation data that will test expectations for a December Federal Reserve rate hike. Following hawkish signals from Fed officials keeping a 25- or even 50-basis-point tightening move on the table after sticky core CPI prints, investors are looking to today’s Producer Price Index (PPI) release for fresh direction on Treasury yields and dollar strength.
Meeting & Conferences of Note:
- Sellside Conferences:
- JP Morgan U.S. Opportunities Forum
- Shareholder Meetings: CODX, FLYE, JSPR, MOD, SYY of note.
- Top Analyst, Investor: EPRX, RVTY of note.
- Fireside Chat: None of note.
- FDA Presentation: None of note.
- R&D Day: None of note.
-
Meetings:
- American Academy of Optometry Conference
- American College of Allergy Asthma and Immunology
- StoneX Sintercafe
Upgrades & Downgrades:
The recommendations listed below in this “Upgrade/Downgrade” section are compiled from what we believe are Tier I, II and III firms. Recommendations posted are taken from a variety of sources each day and we only post upgrades or significant initiations as well as downgrades to underweight or sell. The purpose of this posting is to make the reader aware of market-moving recommendations. None of these recommendations should be interpreted as actual recommendations from CAPIS or its employees.
Upgrades: ADSK, IBP, STE of note.
Downgrades: ARE, FND, LOW, NHI of note.
Prediction Market: October PPI > 0.4% 69%, >0.50% 43% (Month over Month)