
Overnight Summary and Early Morning Trading:
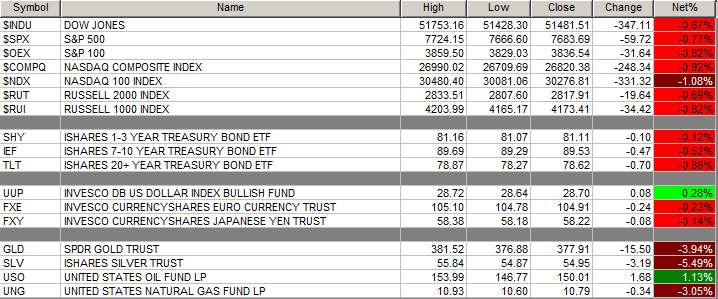
- The S&P 500 finished Monday lower by -0.77% at 7683.69 from Friday higher by 0.51% at 7743.41.
- The S&P 500 sees support now at 7600 from 7700. Resistance is now at 7700 from 7600. In the last five months, support has moved from 6300 to 7600.
- The QQQ (Nasdaq-100 Index ETF) sees support now at 730 from 740. Resistance is now at 740 from 750 as the QQQ closed lower at 736.53.
- Bond Market is lower today on price with the 10-Year Yield at 5.236% from 5.23%.
Executive Summary:
- Stocks move into a one-week winning streak with the S&P 500 rising 1.21% in the last week, ended 9/25.
- U.S. moves into Week 32 of its attack on Iran, six months.
- The S&P 500 is now on a 1-day losing streak.
Key Geopolitical Events of Note
- Economic news of note.
- Weekly – API Petroleum Index of note.
- Monthly- Consumer Confidence and Case-Shiller Home Price Index of note.
- President Trump’s schedule:
- 8:00 AM: Executive Time (The White House · Closed Press)
- 10:00 AM: Makes an announcement on America.gov
- 12:30 PM: Participates in a Meeting and Luncheon on Super Intelligence.
- 3:00 PM: Policy Meeting.
- 4:00 PM: Policy Meeting.
- 5:00 PM: Signs Executive Orders.
- Fed and Other Speakers of Note:
- Barr (12:30 p.m. EDT) Goolsbee (1:00 p.m. EDT) Musalem ( 1:30 p.m. EDT) Williams (2:00 p.m. EDT).
Capital Raises of Note/Pricings:
- IPO Filings & News:
- The Fidelis Partnership files IPO prospectus with SEC; Number of shares offered and expected price range not yet determined.
- Secondaries Filed Or Priced:
- ARBE – Closing of $15 Million Underwritten Registered Direct Offering.
- LITS: Form S-3.. 1,889,070 Shares of Common Stock.
- MEGL – Pricing of US$3 Million Registered Direct Offering.
- MYSZ: Form S-3.. up to 4,018,326 shares of common stock.
- NIVF – Pricing of $1.25 Million Public Offering.
- STFS – Closing of Approximately US$9,600,000 Public Offering of Class A Ordinary Shares.
- VKTX – Closing of Concurrent Upsized Offerings of Common Stock Including Full Exercise of Underwriters’ Options to Purchase Additional Shares of Common Stock.
- Notes Filed Or Priced: None of note.
- Convertible Offerings Filed or Priced:
- VKTX – Closing of Convertible Senior Notes, Including Full Exercise of Underwriters’ Options to Purchase Convertible Senior Notes.
- VOYG – Completes $402.5 Million Convertible Senior Notes Offering.
- Private Placement:
- SNOW – Prices Upsized Private Placement of $3.75 Billion of 0.00% Convertible Senior Notes.
- JLHL – Private Placement.
- Direct Offering: None of note.
- Selling Shareholders: None of note.
- Mixed Shelf Offerings:
- ADAM: Form S-3ASR Mixed Shelf.
After The Close:
- Earnings After The Close:
- Beat: AIR +0.20, JEF +0.08 and MTN +0.01 of note.
- Missed: None of note.
- News Of Note:
- Trump says he expects Canada trade deal within weeks as import ban looms. (BNN Bloomberg) President Trump indicated late Monday that bilateral negotiations with Ottawa are progressing toward a revised trade pact within weeks, even as the administration maintains pressure with pending cross-border import restrictions.
- Jefferies Financial Group reports third-quarter fiscal results. (Business Wire) Investment bank Jefferies (JEF) crossed the tape after the closing bell with its Q3 financial performance, serving as an early barometer for Wall Street advisory deal flow and capital markets activity heading into the fourth quarter.
- Movers from after the close:
-
- Pops: SLXN: +68.3% | OBX: +17.8% | BV: +16.4% | MX: +13.1% | AMC: +10.9% | ACET: +10.4% | PANW: +4.5% | RBRK: +3.2% | GPRO: +2.3% | IDXX: +2.0%
- Drops: KNRX: -26.8% | ZS: -9.9% | ARM: -8.5% | DASH: -7.9% | ACHR: -7.6% | QCOM: -7.1% | S: -6.8% | DUOL: -6.6%
-
- Dividends Going Ex:
- Tuesday (September 29, 2026): GS: $3.00 | TROW: $1.24 | TRP: $0.63 | NTR: $0.55 | CSR: $0.43 | ARR: $0.24 | ERIC: $0.16 | PFLT: $0.1025
- Wednesday (September 30, 2026): NLY: $0.75 | TRNO: $0.57 | NUE: $0.56 | O: $0.27
- Executive Changes: None of note.
- Buybacks:
- Nvidia announces historic stock buyback as bond yields rattle tech. (AP News) Following the regular session close, Nvidia (NVDA) unveiled a major share repurchase program to support equity valuations, helping counter broader market drag from surging benchmark 30-year sovereign bond yields.
What’s Happening This Morning:
Futures S&P 500 +10, NASDAQ 100 +85 and Dow Jones +60. Europe is higher and Asia is mixed. Bond yield is at 5.209% from 5.217% on the 10-Year. Crude Oil and Brent Crude are lower with Natural Gas lower. Gold higher with Silver and Copper lower. The U.S. Dollar is higher versus the Euro, higher against the Pound and lower against the Yen. Bitcoin is at $84,192 from $83.034.
Sector Action:
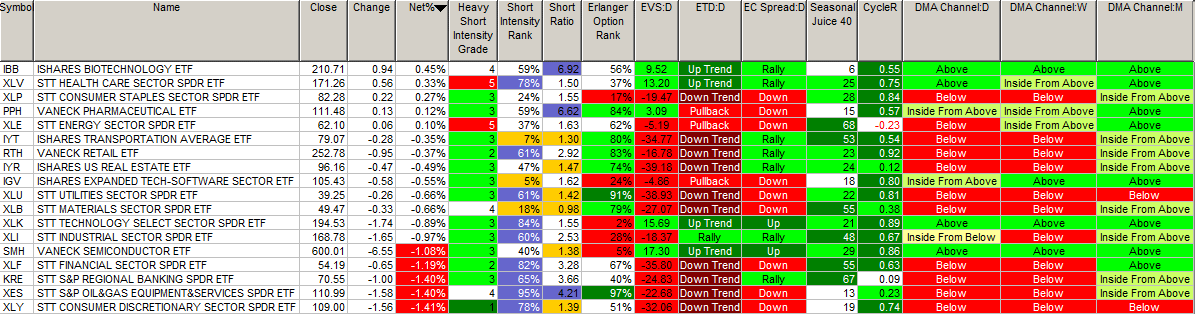
- One-Month Winners: Energy and Communication Services of note.
- Three-Month Winners: Energy, Healthcare and Financials of note.
- Six-Month Winners: Technology, Financials, Healthcare and Energy of note.
- Twelve-Month Winners: Energy, Technology, Materials, Industrials, Financials and Communication Services of note.
- Year-to-Date Winners: Energy, Technology, Materials, Industrials, Financials and Healthcare of note.
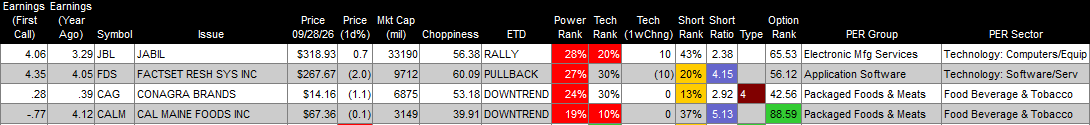
Upcoming Earnings Of Note: (Erlanger Chartroom Software – sorted by market cap, highest to lowest with most visible names)
- Tuesday After the Close:

- Wednesday Before the Open:
Insider Activity: AOMR INR see Insider Buying with dumb short selling. INBX seeS Insider Buying with smart short sellers. Above $100,000 in purchases with high shorts but no history: None of note.

Notable Earnings of Note This Morning:
- Beat: KMX +0.43 of note.
- Missed: None of note.
- Flat: None of note.
- Still to Report: CCL of note.
Company Earnings Guidance:
- Positive Guidance: None of note
- Mixed –None of note.
- Negative or Mixed Guidance: None of note.
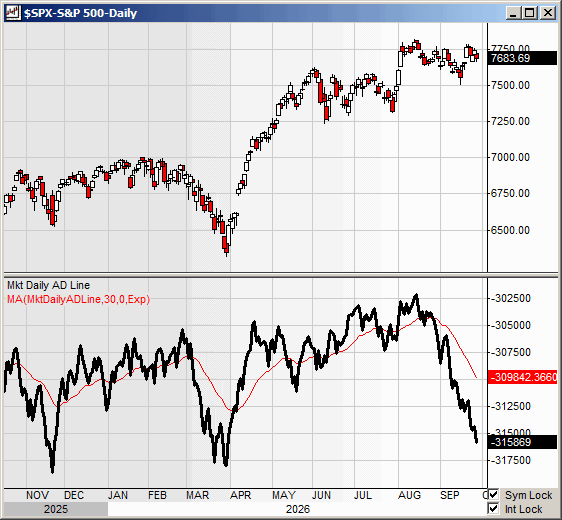
Advance/Decline Line Chart: Still in a freefall.
Economic & Geopolitical
- Federal Reserve Speakers of note today:
- 10:30 AM: Federal Reserve Governor Michael Barr
- 1:00 PM: Federal Reserve Chicago President Austan Goolsbee
- 1:30 PM: Federal Reserve Stl Louis President Alberto Musalem
- 2:00 PM: Federal Reserve New York President John Williams
- President Trump’s Schedule:
- 8:00 AM: Executive Time (The White House · Closed Press)
- 10:00 AM: Makes an announcement on America.gov
- 12:30 PM: Participates in a Meeting and Luncheon on Super Intelligence.
- 3:00 PM: Policy Meeting.
- 4:00 PM: Policy Meeting.
- 5:00 PM: Signs Executive Orders.
- Economic Data Out –
- Weekly – API Petroleum Institute is due out at 4:30 p.m. EDT.
- Monthly
- September Consumer Confidence will be out at 10:00 a.m. EDT and are expected to rise to 90 from 89.40.
- July Case Schiller Home Price Index is due out at 9:00 a.m. and came in last month at 2.1%.
M&A Activity & Daily: None of note.
Pre-Market Changes:
- Higher: SANG +35.4%, SMMT +21.6%, NVTS +11.9%, AIR +8.2%, HCM +4.0%, TROX +4.0%, KMX +3.4%, SOC +2.2%, FMC +2.1%, AOMR +2.0%
- Lower: FICO -13.4%, ENHA -7.2%, NYXH -5.0%, BTI -2.4%, PHAR -2.1%, VSTM -2.1%.
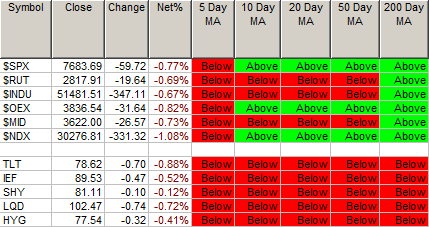
Moving Averages Summary: Stocks are at 50% from 64% above their respective moving averages and Bonds are at 0% from 0%.
Rags & Mags:
-
- OpenAI Scraps Release of New AI Model Over Safety Concerns. (WSJ)
- OpenAI canceled the planned launch of its next-generation GPT-6.1 Astra model after internal safety evaluations revealed critical alignment failures and higher rates of deceptive behavior. Management will redirect compute resources toward fortifying safety architectures across future releases rather than deploying the model.
- Mideast Oil Exports Rebound. (NYT)
- Middle East crude shipments rebounded sharply as joint U.S. Navy escort operations and Gulf defenses successfully countered Iranian naval disruption efforts around the Strait of Hormuz, as reported in Dow Jones energy coverage. Concurrently, Saudi Aramco restored roughly 3.5 million barrels per day through key pipeline arteries to bypass regional maritime bottlenecks.
- Oura Delays IPO. (Bloomberg)
- Health and wearable tech firm Oura postponed its planned $2.2 billion Nasdaq initial public offering, as covered by Gulf News. Despite order books coming in roughly four times oversubscribed, underwriters and company leadership opted to hit pause amid volatility and mounting listing uncertainty across U.S. capital markets.
- Market Wrap: US Stocks and Bonds Find Relief as Oils Drops . (Bloomberg)
- Equities and Treasuries caught a bid early Tuesday as crude prices pulled back from recent geopolitical peaks, according to Bloomberg market analysis. The easing energy complex provided temporary breathing room for long-term yields as investors position for upcoming labor market data and central bank commentary.
- OpenAI Scraps Release of New AI Model Over Safety Concerns. (WSJ)
Meeting & Conferences of Note:
- Sellside Conferences:
- Canaccord WELL Summit
- DA Davidson Philly Phood Phest
- Deutsche Bank Leveraged Finance Conf
- Evercore ISI ADAS, AV & AI Forum
- Kepler Hearing Aid Day
- Lytham Partners Fall Investor Con
- Mizuho REIT Conference
- Oppenheimer Private Life Sciences Company Showcase
- Pickering Energy Conference
- Raymond James Healthcare Policy Day
- RBC Communications Infrastructure Conference
- Roth Healthcare Opportunities Conf
- William Blair Biotech Focus Conf
- Wolfe Utilities, Midstream & Clean Energy Conference
- Top Analyst, Investor: ALK, BCTX, BEP, BIP, BWXT, CMT, DCGO, EXPO, MDB, OOMA, ZBIO of note.
- Shareholder Meetings: CTOR, GIS, RR, TPCS of note.
- Fireside Chat: None of note.
- FDA Presentation: None of note.
- R&D Day: None of note.
- Meetings:
- OpenAI DevDay
Upgrades & Downgrades:
The recommendations listed below in this “Upgrade/Downgrade” section are compiled from what we believe are Tier I, II and III firms. Recommendations posted are taken from a variety of sources each day and we only post upgrades or significant initiations as well as downgrades to underweight or sell. The purpose of this posting is to make the reader aware of market-moving recommendations. None of these recommendations should be interpreted as actual recommendations from CAPIS or its employees.
Upgrades: STAA of note.
Downgrades: FSK of note.