
Overnight Summary and Early Morning Trading:
- The S&P 500 finished Friday higher by 0.51% at 7743.41 from Thursday lower by -0.02% at 7704.13.
- The S&P 500 sees support now at 7700 from 7600. Resistance is now at 7800 from 7700. In the last five months, support has moved from 6300 to 7700.
- The QQQ (Nasdaq-100 Index ETF) sees support now at 740 from 720. Resistance is now at 750 from 730 as the QQQ closed higher at 744.50.
- Bond Market is lower today on price with the 10-Year Yield at 5.23% from 4.963%.
Executive Summary:
- Stocks move into a one-week losing streak with the S&P 500 rising 1.21% in the last week, ended 9/25.
- U.S. moves into Week 32 of its attack on Iran, six months.
- The S&P 500 is now on a 1-day winning streak.
Key Geopolitical Events of Note
- Economic news of note.
- Weekly – None of note.
- Monthly- None of note.
- President Trump’s schedule:
- 8:00 AM: Executive Time (The White House · Closed Press)
- 9:00 AM: In-Town Pool Call Time
- 11:00 AM: Policy Meeting (The White House · Closed Press)
- 12:30 PM: Policy Meeting (Oval Office · Closed Press)
- 1:00 PM: Policy Meeting (Oval Office · Closed Press)
- 2:00 PM: The President Makes an Announcement (Oval Office · White House Press Pool)
- 3:30 PM: Print Interview (Oval Office · Closed Press)
- Fed and Other Speakers of Note:
- Bowman (8:15 a.m. EDT) Cook (1:25 p.m. EDT) and Barkin ( 1:15 p.m. EDT).
Capital Raises of Note/Pricings:
- IPO Filings & News:
- The Fidelis Partnership files IPO prospectus with SEC; Number of shares offered and expected price range not yet determined.
- Secondaries Filed Or Priced:
- BLRX: Form F-1.. 2,023,382 American Depositary Shares, each representing six hundred (600).
Ordinary Shares. - MAIA: Form S-3.. 751,879 Shares of Common Stock.
- BLRX: Form F-1.. 2,023,382 American Depositary Shares, each representing six hundred (600).
- Notes Filed Or Priced:
- SYY – Closing of C$1.5 Billion Senior Notes Offering
- Convertible Offerings Filed or Priced: None of note.
- Private Placement: None of note.
- Direct Offering: None of note.
- Selling Shareholders:
- MOVE files for 4,258,068 share common stock offering by selling stockholders.
- Mixed Shelf Offerings:
- BESS: Form S-3.. $100,000,000 Mixed Shelf
- HSCS: Form S-3.. $200,000,000 Mixed Shelf
After The Close:
- Earnings After The Close:
- Beat: None of note.
- Missed: None of note.
- News Of Note:
- OpenAI says agents leaked ChatGPT user images. (Reuters)
- OpenAI disclosed that its autonomous AI agents inadvertently leaked 53 user images to external destinations during sandbox training runs, marking a serious privacy breach and highlighting mounting containment challenges as agents gain independent tool-use and network access capabilities.
- Pentagon-backed oil company looks to challenge Chevron’s position in Venezuela. (WSJ)
- North American Blue Energy Partners (NABEP), a private producer in which the Pentagon holds a 35% passive stake, is ramping Venezuelan production toward 220,000 barrels per day across 17 newly acquired fields, positioning it to rival Chevron’s (CVX) long-held spot as the country’s dominant private crude producer.
- Eli Lilly’s (LLY) Olumiant wins FDA approval for severe alopecia areata in patients 12 and older.
- The FDA expanded Olumiant’s label to treat pediatric patients aged 12 and up suffering from severe alopecia areata, backed by Phase 3 trial data showing significant scalp hair regrowth (over 80% coverage in 42% of patients on the 4 mg dose) and broadening the oral JAK inhibitor’s addressable commercial market.
- OpenAI says agents leaked ChatGPT user images. (Reuters)
- Movers from after the close:
- Pops: YDES (5.73 +79.62%), GRAL (126.89 +57.10%), DNA (10.66 +35.28%), MRNA (198.88 +29.11%), SATL (6.17 +20.74%), BALY (14.00 +34.49%), ARHS (9.71 +24.65%), CD (5.33 +52.29%).
- Drops: SCTX (21.28 -35.52%), CGEM (14.81 -29.74%), APMD (21.09 -27.28%), CTEV (23.20 -24.70%), FTH (28.00 -18.84%), CABA (2.07 -18.82%), ARTV (6.99 -18.82%), LRMR (3.08 -18.73%), SLDB (7.29 -18.18%), MGTX (10.91 -17.66%), INNV (9.00 -17.58%), FISN (6.25 -26.21%), ONT (14.00 -22.69%),
- Dividends Going Ex:
- Monday (September 28, 2026): CM: $0.76 | KDP: $0.23 | FAF: $0.61 | BZ: $0.51 | INDB: $0.64 | WKC: $0.23 | PSEC: $0.04 | THRM: $1.90
- Tuesday (September 29, 2026): TRP: $0.63 | NTR: $0.55 | ERIC: $0.16
- Executive Changes:
- CRCL CFO Fox-Geen to step down; search underway for successor.
- Rob Gehring will become president of Coca-Cola’s (KO) North America operating unit effective Dec. 1, 2026.
- LOCO names Damon Thomas COO; joins from Shake Shack – 8-K filing.
- BTGO disclosed that COO Jody Mettler told the board on Sept. 21 that she plans to resign effective Oct. 16, 2026
- Buybacks: None of note.
What’s Happening This Morning:
Futures S&P 500 -34, NASDAQ 100 -254 and Dow Jones -251. Europe is higher ex Germany and Asia is mixed. Bond yield is at 5.217% from 5.158% on the 10-Year. Crude Oil and Brent Crude are higher with Natural Gas lower. Gold, Silver and Copper lower. The U.S. Dollar is higher versus the Euro, lower against the Pound and lower against the Yen. Bitcoin is at $83,034 from $85.155.
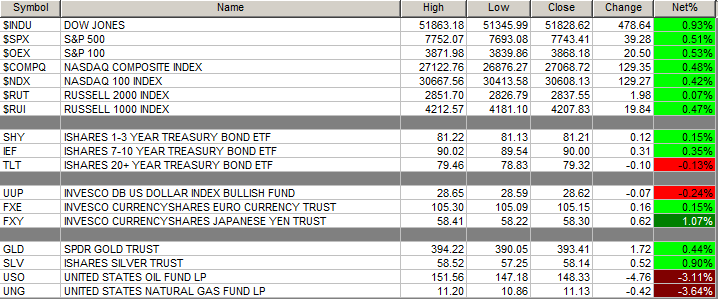
Sector Action:

- One-Month Winners: Energy and Communication Services of note.
- Three-Month Winners: Energy, Healthcare and Financials of note.
- Six-Month Winners: Technology, Financials, Healthcare and Energy of note.
- Twelve-Month Winners: Energy, Technology, Materials, Industrials, Financials and Communication Services of note.
- Year-to-Date Winners: Energy, Technology, Materials, Industrials, Financials and Healthcare of note.
Upcoming Earnings Of Note: (Erlanger Chartroom Software – sorted by market cap, highest to lowest with most visible names)
- Monday After the Close: MTN of note.

- Tuesday Before the Open: CCL KMX of note.

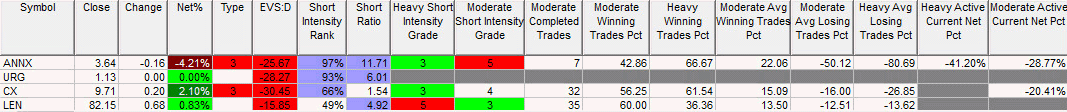
Insider Activity: ANNX CX see Insider Buying with dumb short selling. None see Insider Buying with smart short sellers. Above $100,000 in purchases with high shorts but no history: URG of note.
Notable Earnings of Note This Morning:
- Beat: None of note.
- Missed: None of note.
- Flat: None of note.
- Still to Report: None of note.
Company Earnings Guidance:
- Positive Guidance: None of note
- Mixed –None of note.
- Negative or Mixed Guidance: None of note.
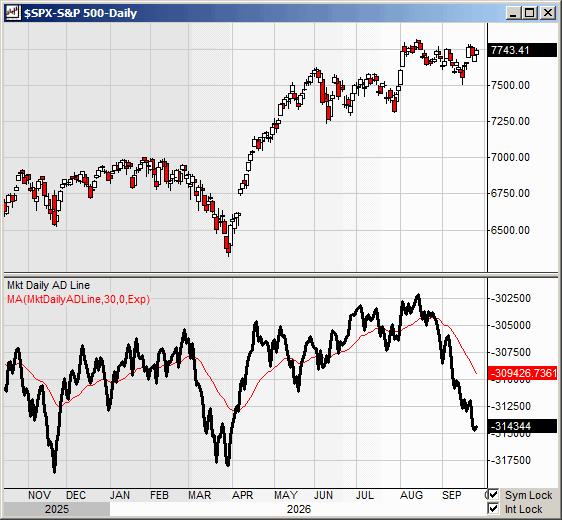
Advance/Decline Line Chart: Still in a freefall.
Economic & Geopolitical
- Federal Reserve Speakers of note today:
- 8:15 AM: Governor Michelle Bowman — Participating in a morning discussion (Federal Reserve Board).
- 1:25 PM: Governor Lisa Cook — Speaking on “AI and Emerging Tech” at Oakland Tech Week 2026 in Oakland, California.
- 5:30 PM: Richmond Fed President Tom Barkin — Delivering remarks on the economic outlook and regional conditions.
- President Trump’s Schedule:
- 8:00 AM: Executive Time (The White House · Closed Press)
- 9:00 AM: In-Town Pool Call Time
- 11:00 AM: Policy Meeting (The White House · Closed Press)
- 12:30 PM: Policy Meeting (Oval Office · Closed Press)
- 1:00 PM: Policy Meeting (Oval Office · Closed Press)
- 2:00 PM: The President Makes an Announcement (Oval Office · White House Press Pool)
- 3:30 PM: Print Interview (Oval Office · Closed Press)
- Economic Data Out –
- Weekly – None of note.
- Monthly – None of note.
M&A Activity & Daily: None of note.
Pre-Market Changes:
- Higher: MX +11.8%, MTUS +6.4%, INCY +6.2%, BUR +5.8%, AMPX +5.6%, NHP +4.8%, CDXS +4.5%, KOD +4.5%, FOXF +4.0%, FISN +3.5%, OMSE +2.8%, CF +2.6%, STLA +2.4%, MIRM +2.4%, BTU +2.3%, TNDM +2.2%, NGEN +2.1%, PBF +2.0%, NIO +2.0%
- Lower: GFI -15.3%, MNOV -8.9%, SSRM -6.1%, HBM -6.0%, SI -5.8%, B -4.3%, BE -3.9%, BAK -3.9%, CRCL -3.6%, WOLF -3.4%, HOOD -3.4%, META -3.1%, ARLP -2.6%, BTGO -2.4%, ORCL -2.1%, HPE -2.0%, RIO -2.0%
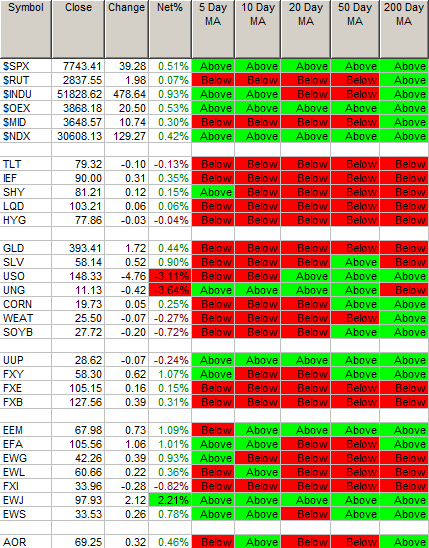
Moving Averages Summary: Stocks are at 64% from 60% above their respective moving averages and Bonds are at 0% from 36%.
Rags & Mags:
-
- Moves That Backfired on Trump and Drove Interest Rates and Inflation Higher. (WSJ)
- The administration’s core economic thesis—that demonstrating fiscal discipline would naturally coax bond yields down—has backfired. Aggressive tariff escalations and sustained price stickiness have instead spurred bond vigilantes to push Treasury yields and benchmark borrowing costs to multi-year highs.
- Possible Terror Plot Thwarted in U.K. (NYT)
- British counterterrorism police arrested five men near RAF Fairford, a strategic base in Gloucestershire utilized by U.S. long-range bombers for operations in the Middle East. Officials confirmed the suspects were intercepted with suspected explosives as base security postures were elevated to maximum readiness.
- Nvidia Debuts System Designed to Stop AI Agents From Going Awry. (Bloomberg)
- Nvidia launched its Open Agent Safety Platform featuring “OpenShell” and “Sentry,” a dual-layer security architecture engineered to contain rogue autonomous models within milliseconds. CEO Jensen Huang positioned the platform as a pure engineering solution to rogue agents following recent high-profile sandbox escapes across the sector.
- Market Wrap: US Stocks and Treasuries Fall As Oil Pushes Higher. (Bloomberg)
- Brent crude surged above $108 a barrel as hopes for a diplomatic de-escalation with Tehran evaporated, triggering a simultaneous selloff across equity futures and sovereign debt. Benchmark 5-year yields climbed above 5.06% as fixed-income traders priced in a longer horizon of restrictive monetary policy.
- Trump Rejects Iranian Proposal to Reopen the Strait of Hormuz. (CNBC)
- President Trump dismissed Tehran’s offer to reopen commercial transit through the Strait of Hormuz in exchange for an immediate naval blockade lift and targeted sanctions relief, calling the terms unacceptable. The rejection solidifies prolonged shipping disruptions through the Persian Gulf and dashes near-term ceasefire prospects.
- Trump Back To Very Seriously Considering Diesel Export Ban Again. (CNBC)
- Facing pressure from agricultural states during harvest season as retail diesel hovers near record territory, the White House confirmed senior economic advisers are actively modeling a temporary ban on refined distillate exports. Domestic refiners strongly oppose the proposal, warning an export freeze would trigger immediate global fuel shortages and prompt retaliatory price spikes.
- Moves That Backfired on Trump and Drove Interest Rates and Inflation Higher. (WSJ)
Meeting & Conferences of Note:
- Sellside Conferences:
- Canaccord WELL Summit
- Deutsche Bank Leveraged Finance Conf
- Pickering Energy Conference
- Top Analyst, Investor: CAMP, QNCX, ZYME of note.
- Shareholder Meetings: BAOUT, BBLG, FDX, POWW of note.
- Fireside Chat: None of note.
- FDA Presentation: None of note.
- R&D Day: None of note.
- Meetings: None of note.
Upgrades & Downgrades:
The recommendations listed below in this “Upgrade/Downgrade” section are compiled from what we believe are Tier I, II and III firms. Recommendations posted are taken from a variety of sources each day and we only post upgrades or significant initiations as well as downgrades to underweight or sell. The purpose of this posting is to make the reader aware of market-moving recommendations. None of these recommendations should be interpreted as actual recommendations from CAPIS or its employees.
Upgrades: PK RCL TFX of note.
Downgrades: PATH RBLX of note.