
Overnight Summary and Early Morning Trading:
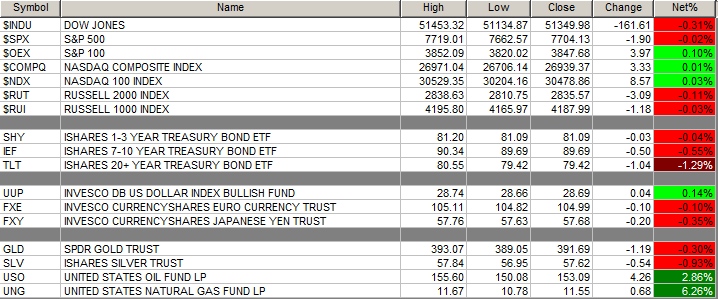
- The S&P 500 finished Thursday lower by -0.02% at 7704.13 from Wednesday lower by -0.75% at 7706.03 from Tuesday flat at 7764.64.
- The S&P 500 sees support now at 7700 from 7600. Resistance is now at 7800 from 7700. In the last five months, support has moved from 6300 to 7700.
- The QQQ (Nasdaq-100 Index ETF) sees support now at 740 from 720. Resistance is now at 750 from 730 as the QQQ closed lower at 741.10.
- Bond Market is higher today on price with the 10-Year Yield at 4.963% from 4.935%.
Executive Summary:
- Stocks move into a two-week losing streak with the S&P 500 falling -0.08% in the last week, ended 9/18.
- U.S. moves into Week 31 of its attack on Iran, six months.
- The S&P 500 is now on a 3-day losing streak.
Key Geopolitical Events of Note
- Economic news of note.
- Weekly – Baker Hughes Rig Count of note.
- Monthly- Durable Orders and U of Mich Consumer Sentiment Final (Go Blue!!) of note.
- President Trump’s schedule:
- 8:00 AM: Executive Time (The White House)
- The President and the First Lady greet the President of the People’s Republic of China and Madame Peng at 10:30 a.m. EDT and then have tea at 10:35 a.m. EDT.
- The President and the First Lady participate in a Site Visit (National Archives) with the President of the People’s Republic of China and Madame Peng at 11:30 a.m. EDT.
- Participates in a Policy Meeting at 2:00 p.m. EDT.
- Participates in Signing Time at 4:30 p.m. EDT.
- Participates in a Policy Meeting at 5:00 p.m. EDT.
- Fed and Other Speakers of Note:
- Schmid (9:20 a.m. EDT) and Hammack ( 2 p.m. EDT).
Capital Raises of Note/Pricings:
- IPO Filings & News:
- City Therapeutics files IPO prospectus with the SEC; Number of shares to be offered and expected price range not yet determined.
- SCNI: Form F-1.. 2,706,450 American Depositary Shares representing 108,258,000,000 Ordinary Shares.
- Secondaries Filed Or Priced:
- BMRA: Form S-3.. 1,403,705 Shares of Common Stock.
- IMCC – Closing of US$1.31 Million Registered Direct Offering of Common Shares.
- Notes Filed Or Priced:
- GLNG – Pricing of $500 Million Offering of Senior Notes due 2031.
- Convertible Offerings Filed or Priced:
- DK – Pricing of $400 Million of Convertible Senior Notes.
- Private Placement: None of note.
- Direct Offering: None of note.
- TMCR files for 27,796,079 common share offering by selling securityholders.
- Mixed Shelf Offerings:
- ESEA files for $400 million mixed securities shelf offering.
- PINE: Form S-3.. $400,000,000 Mixed Shelf
After The Close:
- Earnings After The Close:
- Beat: COST +0.21
- Missed: None of note.
- News Of Note:
- Celanese (CE) raises prices for select engineered materials products.
- Akamai (AKAM) signs $11.6 billion seven-year cloud deal with Anthropic.
- Costco (COST) beats on earnings and revenues.
- Blue Origin closes first-ever outside capital raise of $10 billion, putting space company’s valuation at $140 bln.
- Movers from after the close:
- Pops: AKAM +19.1%, PRME +12.4%, WTTR +11.5%,PPLI +9.5%, FTHM +5.8%,STAA +4.7%, CNP +3.3%.
- Drops: SCHL -12.1%, LGCY -8.4%, ZS -3.6%.
- Dividends Going Ex:
- Friday (September 25, 2026): VMI: $0.77 | MDT: $0.72 | LIEN: $0.34 | BZ: $0.255 | PPHC: $0.117
- Monday (September 28, 2026): CM: $0.76 | KDP: $0.23 | FAF: $0.61 | BZ: $0.51 | INDB: $0.64 | WKC: $0.23 | PSEC: $0.04 | THRM: $1.90
- TMUS ncreases quarterly cash dividend to $1.17/share from $1.02/share.
- Executive Changes:
- EC names Joaquín Gutiérrez Caballero permanent CEO.
- Buybacks
- STAA authorizes $50 million share repurchase program.
- LEA boosts buyback authorization to $1.5 billion, extends program through 2029.
What’s Happening This Morning:
Futures S&P 500 +19, NASDAQ 100 +159 and Dow Jones +91. Europe is higher and Asia is mixed. Bond yield is at 5.158% from 5.131% on the 10-Year. Crude Oil and Brent Crude are higher with Natural Gas higher. Gold and Silver are higher with Copper lower. The U.S. Dollar is lower versus the Euro, lower against the Pound and lower against the Yen. Bitcoin is at $85,155 from $83,434 from $85,535.
Sector Action:
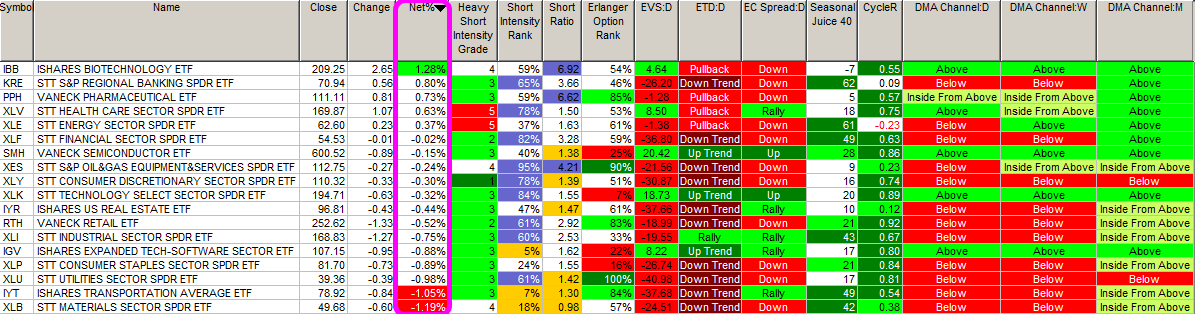
- One-Month Winners: Energy and Communication Services of note.
- Three-Month Winners: Energy, Healthcare and Financials of note.
- Six-Month Winners: Technology, Financials, Healthcare and Energy of note.
- Twelve-Month Winners: Energy, Technology, Materials, Industrials, Financials and Communication Services of note.
- Year-to-Date Winners: Energy, Technology, Materials, Industrials, Financials and Healthcare of note.
Upcoming Earnings Of Note: (Erlanger Chartroom Software – sorted by market cap, highest to lowest with most visible names)
- Friday After the Close: None of note.
- Monday Before the Open: None of note.
Insider Activity: None see Insider Buying with dumb short selling. None see Insider Buying with smart short sellers. Above $100,000 in purchases with high shorts but no history: None of note.
Notable Earnings of Note This Morning:
- Beat: None of note.
- Missed: None of note.
- Flat: None of note.
- Still to Report: None of note.
Company Earnings Guidance:
- Positive Guidance: None of note
- Mixed –None of note.
- Negative or Mixed Guidance: None of note.
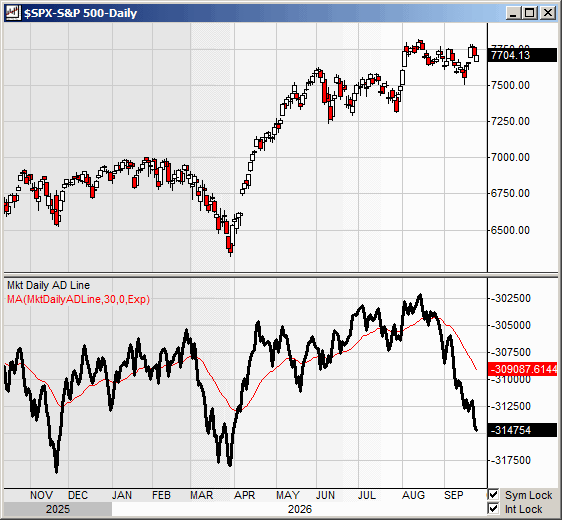
Advance/Decline Line Chart: Still in a freefall.
Economic & Geopolitical
- Federal Reserve Speakers of note today:
- Federal Reserve St. Louis President Jeffrey Schmid speaks at 9:20 a.m. EDT.
- Federal Reserve Cleveland President Beth Hammack speaks at 2:00 p.m. EDT.
- President Trump’s Schedule:
- 8:00 AM: Executive Time (The White House)
- The President and the First Lady greet the President of the People’s Republic of China and Madame Peng at 10:30 a.m. EDT and then have tea at 10:35 a.m. EDT.
- The President and the First Lady participate in a Site Visit (National Archives) with the President of the People’s Republic of China and Madame Peng at 11:30 a.m. EDT.
- Participates in a Policy Meeting at 2:00 p.m. EDT.
- Participates in Signing Time at 4:30 p.m. EDT.
- Participates in a Policy Meeting at 5:00 p.m. EDT.
- Economic Data Out –
- Weekly –
- Baker Hughes Rig Count out at 1:00 p.m. EDT.
- Monthly-
- Durable Goods due out at 8:30 a.m. EDT and are expected to fall to -0.40% from 1.10%
- University of Michigan Consumer Sentiment – Final is out at 10:00 a.m. EDT and expected to remain at 47.80.
- Weekly –
M&A Activity & Daily: None of note.
Pre-Market Changes:
- Higher: AKAM +22.0%, PRME +10.4%, PPLI +9.3%, WTTR +5.0%, P +3.9%, TLN +3.1%, FRMI +2.6%, TBN +2.5%, LUNR +2.5%, RGNX +2.1%, FMS +2.0%
- Lower: SCHL -12.0%, ZS -3.6%
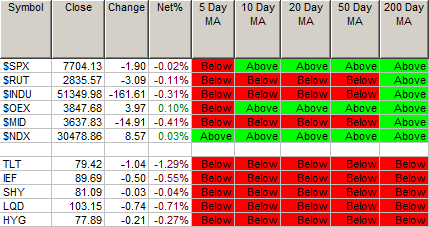
Moving Averages Summary: Stocks are at 60% from 77% above their respective moving averages and Bonds are at 0% from 36%.
Rags & Mags:
- Gulf allies want President Trump to keep pressure on Iran. (WSJ)
- Saudi Arabia and the UAE are privately urging Washington to maintain aggressive economic sanctions and military deterrence against Tehran, cautioning that any premature diplomatic compromises or sanctions relief could embolden Iranian regional proxies.
- The Record ICE Surge That Swept Across America This Summer. (NYT)
- An investigative review reveals federal immigration authorities executed an unprecedented nationwide enforcement sweep over recent months, dramatically escalating workplace raids, detention numbers, and community arrests.
- Trump-Xi Summit Goes Big on Pomp But Small On Substance. (Bloomberg)
- While the high-profile bilateral meeting delivered full state-level pageantry and extended the tariff truce into January, the two leaders concluded talks without tangible breakthroughs on export curbs, Taiwan, or AI governance.
- 60 commercial ships passed through the Strait of Hormuz on Wednesday, the highest volume since July. (The Times of Israel)
- Tanker traffic through the critical maritime chokepoint surged to roughly 22 million barrels of crude in a single 24-hour window, with nearly 40 vessels coordinating directly with U.S. naval escorts amid ongoing regional hostilities.
- Barron’s + on BN BM CAVA and +/- META.
- Barron’s published constructive outlooks on Brookfield Corporation (BN), Beam Global (BM), and CAVA Group (CAVA) citing operational execution and growth tailwinds, while striking a balanced, mixed stance on Meta Platforms (META) over rising capital expenditures against core advertising returns.
Meeting & Conferences of Note:
- Sellside Conferences:
- DA Davidson Diversified Industrials & Services Conference
- Leerink Biopharma Summit
- TD Cowen Energy Conference
- Top Analyst, Investor: EBAY of note.
- Shareholder Meetings: BYRN, CGC, PRKR of note.
- Fireside Chat: None of note.
- FDA Presentation: None of note.
- R&D Day: None of note.
- Meetings:
- UN General Assembly
Upgrades & Downgrades:
The recommendations listed below in this “Upgrade/Downgrade” section are compiled from what we believe are Tier I, II and III firms. Recommendations posted are taken from a variety of sources each day and we only post upgrades or significant initiations as well as downgrades to underweight or sell. The purpose of this posting is to make the reader aware of market-moving recommendations. None of these recommendations should be interpreted as actual recommendations from CAPIS or its employees.
Upgrades: FFBC SNPS STEM of note.
Downgrades: CMCSA NKE TWLO of note.