
Overnight Summary and Early Morning Trading: Today is a limited version due to travel. Thursday and Friday will be normal production.
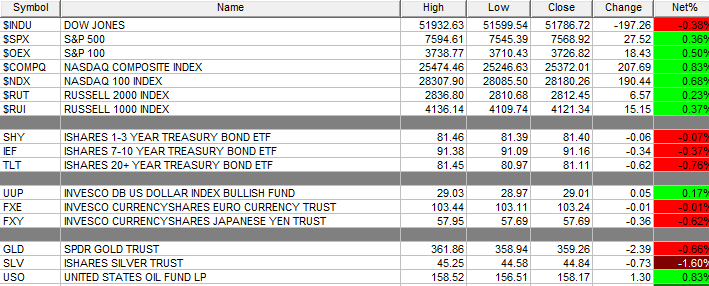
- The S&P 500 finished Tuesday higher by 0.36% at 7568.92 from Monday lower by -0.51% at 7541.40.
- The S&P 500 sees support now at 7500 from 7700. Resistance is now at 7600 from 7800. In the last six months, support has moved from 6300 to 7500.
- The QQQ (Nasdaq-100 Index ETF) sees support now at 680 from 690. Resistance is now at 690 from 700 as the QQQ closed lower at 681.09 from 690.49.
- Bond Market is at 4.931% from 4.931%.
Executive Summary:
- Bond Market have recovered yields from recent highs and closed the week at 4.933% from 4.999%. This is a big deal now back to 4.75% in the next few weeks?
- Stocks moved into a three week losing streak with the S&P 500 falling last week, ended 10/30 by -0.57%.
- U.S. moves into Week 39 of its attack on Iran, eight months.
- The S&P 500 lost -1% on four days last month. We are clustering on the downside, which is not good BUT we start a new month this week? Will it end??
Key Geopolitical Events of Note
-
Economic news of note.
- Weekly – Crude Oil Inventories of note.
- Monthly- ADP Report, Global U.S. Services PMI, ISM Non-Manufacturing Index of note.
-
President Trump’s schedule:
- Participates in Executive Time at 8:00 a.m. EDT.
- Participates in a Policy Meeting at 11:00 a.m. EDT.
- Participates in a Policy Meeting at 1:30 p.m. EDT.
- Participates in a Policy Meeting at 2:00 p.m. EDT.
- Participates in a Policy Meeting at 3:30 p.m. EDT.
- Fed and Other Speakers of Note: None of note.
Capital Raises Announced After The Close:
- IPO Filings & News: None of note.
- Notes Files: None of note.
-
Secondaries Filed Or Priced:
- CVI – Pricing of Offering of Common Stock.
- IDA: Form S-3ASR – 300,000 Shares of Common Stock.
- MDWD – $15 Million Bought Deal Offering of Ordinary Shares.
- Convertible Offerings Filed or Priced: None of note.
- Private Placement: None of note.
- Direct Offering: None of note.
- Selling Shareholders: None of note.
-
Mixed Shelf Offerings:
- ARVN: Form S-3.. $400,000,000 Mixed Shelf.
- IMSR: Form S-3.. $500,000,000 Mixed Shelf.
- LVS: FORM S-3ASR – Mixed Shelf Offering.
- SURG: Form S-3.. $100,000,000 Mixed Shelf.
After The Close:
-
Earnings After The Close:
- Beat: MDGL +2.76, MPC +1.56, BNTX +1.09, LDOS +0.59, EXPD +0.43, DD +0.22, HSIC +0.20, of note.
- Missed: AHCO -1.08, SUN -0.7, RCE -0.24, BEAM -0.13, ET -0.08 of note.
- Inline: None of note.
-
Dividend Ex Update:
- Wednesday: EQT: $0.17 | BRO: $0.18 | MUSA: $0.72 | HFWA: $0.25 | MCBS: $0.31
- Thursday: STRC: $0.03 | WCN: $0.39 | SYF: $0.34 | CCK: $0.35 | WTFC: $0.55 | IDA: $0.90 | AWI: $0.37 | CAG: $0.17 | MATX: $0.38 | SIMO: $0.57 | BANR: $0.52 | MTX: $0.13 | TRS: $0.04 | DEA: $0.45
-
News Of Note:
- Early election results predict that Democrats did well.
-
Biggest Movers Up & Down Last Week
- Pops: ANET +12.6%, DUOL +11.1%, PCOR +10.9%, ARDX +9.6%, FLYW +9.5%, AMD +7.6%, SMCI +7.5%
- Drops: DOX -42.5%, SWKS -17.2%, LIME -10.3%, PXED -9.6%, UNM -9.4%, FRSH -7.7%, CAR -7.4%
-
Buybacks:
- JXN boosts common share repurchase authorization by $1 bln, declares Q4 common dividend of $0.90/share
-
Executive Changes:
What’s Happening This Morning:
Futures S&P 500+73, NASDAQ +128 and Dow Jones +876. Europe is higher while Asia is mixed. Bond yield is at 4.917% from 4.937% on the 10-Year. Crude Oil and Brent Crude are lower with Natural Gas lower. Gold, Silver and Copper are higher. The U.S. Dollar is lower versus the Euro, lower against the Pound and lower against the Yen. Bitcoin is at $78,136 from $76,980.
Sector Action: 10 sectors higher and 8 lower.
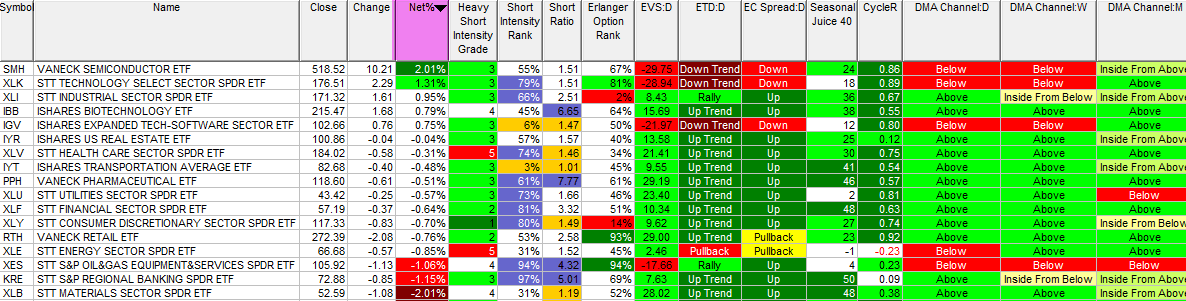
- One-Month Winners: Technology, Utilities, Consumer Cyclical, Consumer Defensive and Communication Services of note.
- Three-Month Winners: Energy, Technology, Materials, Healthcare and Communication Services of note.
- Six-Month Winners: Technology, Energy, Financials, Healthcare and Consumer Defensive of note.
- Twelve-Month Winners: Energy, Technology, Materials, Industrials, Financials and Communication Services of note.
- Year-to-Date Winners: Energy, Technology, Materials, Industrials, Financials and Healthcare of note.
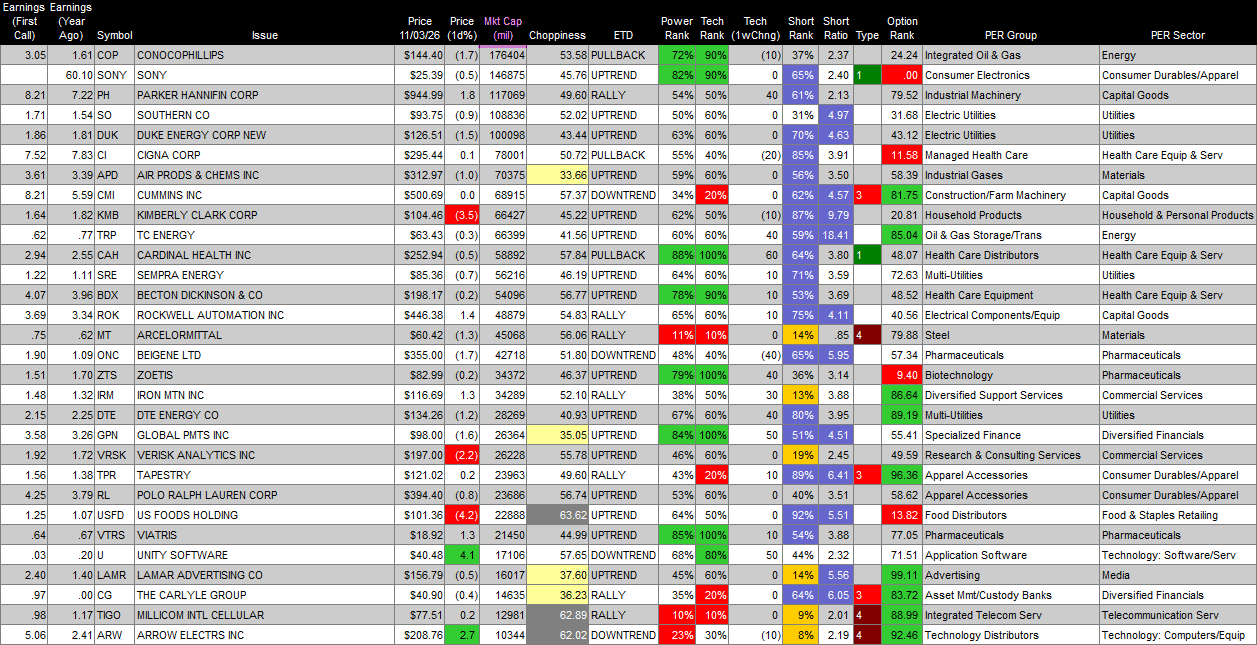
Upcoming Earnings Of Note: (Erlanger Chartroom Software – sorted by market cap, highest to lowest with most visible names)
- Wednesday After the Close: ($10bil and up)
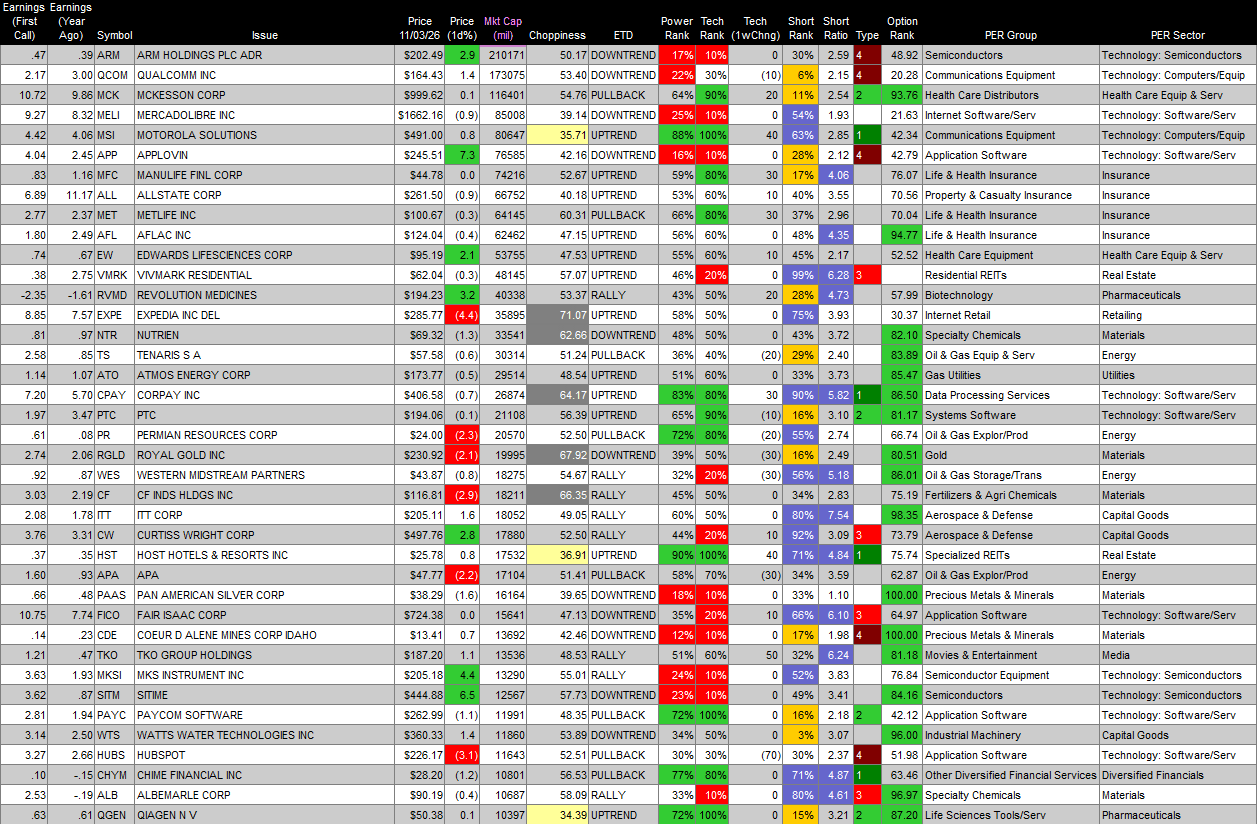
- Thursday Before the Open: ($10bil and up)
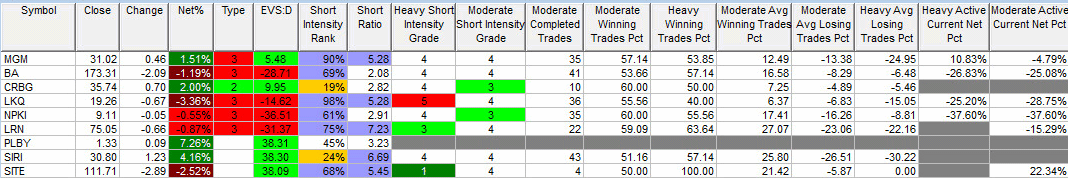
Insider Activity: BA MGM NPKI LRN SITE see Insider Buying with dumb short selling. LKQ see Insider Buying with smart short sellers. Above $100,000 in purchases with high shorts but no history: None of note. With the Government closed yesterday, there were no filings.
Notable Earnings of Note This Morning:
- Beat: NMM +1.05, KMT +0.83, ATHM +0.48, CRCL +0.46, CVS +0.44, SN +0.44, PODD +0.40, CDW +0.28, Q +0.26, SEDG +0.25, FRPT +0.19, MCD +0.19, DDOG +0.17, LIVN +0.17, TKR +0.17, RAL +0.16, W +0.13, VGNT +0.13, ARCB +0.12, SFL +0.12, CRL +0.12, SOLS +0.10, PRGO +0.09, COR +0.08, VSH +0.08, VAC +0.07, TREX +0.07, NICE +0.06, AVNT +0.06, PFGC +0.05, BCRX +0.05, OPLN +0.05, SMG +0.05, YOU +0.04, NYT +0.04, ATS +0.04, KD +0.04, SHLS +0.02, GFS +0.02, UBER +0.02, ZBH +0.02, MTRN +0.02, CIGI +0.02, CWK +0.01, REYN +0.01, NOMD +0.01 of note.
- Missed: BCO (1.86), BRKR (0.98), OC (0.63), MLM (0.52), FLUT (0.50), UTHR (0.30), EMR (0.23), DIN (0.19), EXP (0.19), GOLF (0.15), CRTO (0.15), ADNT (0.13), HZO (0.12), AVA (0.04), WLK (0.04), ESAB (0.03) of note.
- Flat: TBLA +0.00, OPCH +0.00, TRMB +0.00, CAMT +0.00 of note.
- Still to Report: AVT, FIS, GWW, HRMY, HUT, KHC, MSGE, MDLN, MLCO, BTU, RIOT, SWX, XPEL of note.
Company Earnings Guidance:
- Positive Guidance: None of note
- Mixed: None of note.
- Negative or Mixed Guidance: None of note.
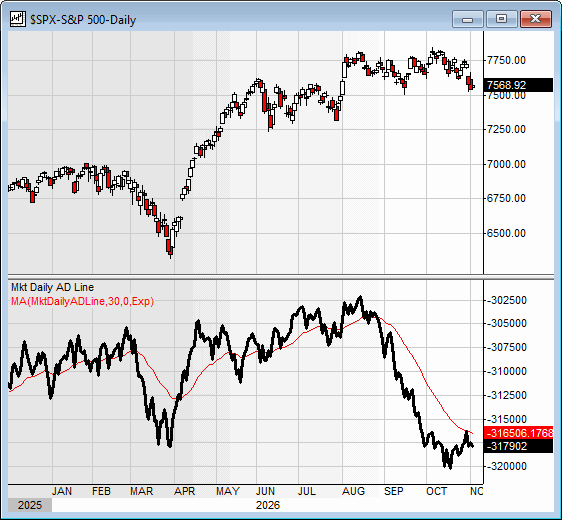
Advance/Decline Line Chart: Still trying to find a meaningful bottom.
Economic & Geopolitical
- Federal Reserve Speakers None of note.
-
President Trump’s Schedule: (see above)
-
Economic Data Due Out
-
Weekly –
- Crude Oil Inventories due out at 10:30 a.m. EDT.
-
Monthly
- October ADP Report are due out at 8:15 a.m. EDT and expected to fall to 75,000 from 90,000.
- September Trade Balance is due out at 8:30 a.m. EDT and expected fall to $-108.4 billion from $-105.6 billion.
- Global U.S. Services PMI for October is due out at 9:45 a.m. EDT and came in last month at 57.90.
- October ISM Non-Manufacturing Index is due out at 10:00 a.m. EDT and expected to fall to 54.8 from 54.90.
-
M&A Activity & Daily: None of note.
Pre-Market Changes:
-
Pre-Market Gainers: FISV +12.46%, BE +9.05%, DD +8.61%, RVTY +7.84%, APP +7.28%, FIX +7.08%, ETN +7.00%, FOXA +6.92%, MPWR +6.78%, FOX +6.56%, GEV +6.49%, ORCL +5.85%, PWR +5.77%, RDDT +5.69%, CIEN +5.54%, COIN +5.53%
-
Pre-Market Decliners: SWKS -13.75%, TSLA -5.83%, TRMB -5.50%, PH -5.35%, VST -5.29%, UDR -4.04%, PLTR -3.92%, ORCL -3.88%, NOC -3.69%, AAPL -1.83%
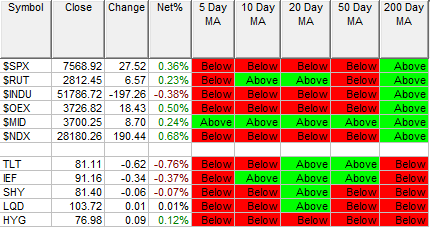
Moving Averages Summary: Stocks are at 40% from 40% above their respective moving averages and Bonds are at 28% from 44%.
Rags & Mags:
- President Trump acknowledged that the Iran war was partially to blame for Republican losses in the midterms. (WSJ)
- President Donald Trump conceded that voter pushback against escalating military action with Iran contributed significantly to broad Republican losses in Tuesday’s midterm elections. Amid public fatigue over expanding conflict around the Strait of Hormuz, rising energy costs, and voter concerns over direct U.S. entanglements abroad, the administration faced intense blowback at the ballot box, blunting the White House’s economic messaging in key battleground districts.
- Democrats rout GOP. (NYT).
- Democrats swept into control of Congress, flipping key House and Senate seats nationwide in a decisive midterm rebuke of Republican governance. Propelled by voter frustration over persistent inflation, high living costs, and foreign military operations, the Democratic wave flipped traditionally conservative Senate ground and reclaimed the legislative majority, fundamentally reshaping the balance of power in Washington for the next two years.
- Trump Has to Govern Through A Mid-Term Meltdown of His Own Making. (Bloomberg)
- The collapse of Republican majorities in Congress leaves President Trump facing divided government and severe legislative gridlock for the remainder of his term. With Democrats securing committee gavels, judicial confirmation power, and budget oversight, the administration will be forced to rely on executive orders and the veto pen as ambitious tax reforms and deregulatory initiatives run into an unyielding congressional roadblock.
- Market Wrap: US Stocks, Bonds Rally After US Vote As Dollar Falls. (Bloomberg)
- Wall Street kicked off post-election trading with broad rallies across U.S. equities and Treasury bonds as investors welcomed the return of Capitol Hill gridlock. Anticipation that a split government will curb aggressive fiscal spending, lower sovereign debt issuance expectations, and prevent disruptive legislative shifts sent bond yields lower and dragged down the U.S. dollar, driving strong relief buying across rate-sensitive and mega-cap tech shares.
- President Trump says he has no immediate plans to strike Iran (FT)
- Following post-election reassessments and limited retaliatory actions around the Strait of Hormuz, President Trump dialed back aggressive rhetoric, stating the U.S. has no immediate plans for expanded offensive strikes against Iranian territory. The de-escalatory signal aims to cool spiking crude oil benchmarks, calm nervous regional allies, and explore potential diplomatic off-ramps to stabilize Persian Gulf transit routes.
Meeting & Conferences of Note:
- Sellside Conferences:
- Gabelli Funds Automotive Symposium
- Goldman Sachs South Africa
- Oppenheimer Oncology Summit
- Wainwright Global Investment Conference
- Shareholder Meetings: CYN, KALA, LRCX, LTRX, MBUU, PAHC of note.
- Top Analyst, Investor: ANNX, IFRX, IP, KMX, RXRX, SNOW of note.
- Fireside Chat: None of note.
- FDA Presentation: None of note.
- R&D Day: None of note.
-
Meetings:
- SEMA Show
- ServiceNow World Forum
- StoneX NAGGL Conference
Upgrades & Downgrades:
The recommendations listed below in this “Upgrade/Downgrade” section are compiled from what we believe are Tier I, II and III firms. Recommendations posted are taken from a variety of sources each day and we only post upgrades or significant initiations as well as downgrades to underweight or sell. The purpose of this posting is to make the reader aware of market-moving recommendations. None of these recommendations should be interpreted as actual recommendations from CAPIS or its employees.
Upgrades: CPNG EW NVTS of note.
Downgrades: AAPL ADBE DRVN FLG GPI XOM of note.
Prediction Market 10/30:
- Kalshi PREDICTED Dems sweep 68%, Dem House Republican Senate 27% Republican Sweep 7.9%, Republican House Democrat Senate 1%. I am going with Democratic House and Republican Senate pays 3.52X. FINAL RESULT DEMOCRATS SWEEP THE HOUSE AND THE SENATE.