Overnight Summary and Early Morning Trading:
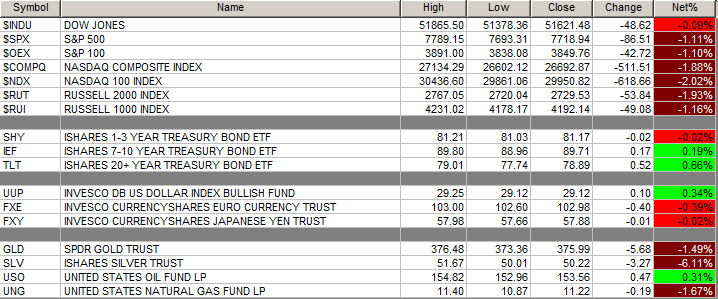
- The S&P 500 finished Wednesday lower by -1.11% at 7718.94 from Tuesday lower by -0.02% at 7805.45.
- The S&P 500 sees support now at 7700 from 7800. Resistance is now at 7800 from 7900. In the last six months, support has moved from 6300 to 7700.
- The QQQ (Nasdaq-100 Index ETF) sees support now at 720 from 740. Resistance is now at 730 from 740 as the QQQ closed lower at 728.95.
- Bond Market is higher today on price with the 10-Year Yield at 5.085% from 5.20%.
Executive Summary:
- Bond Market have recovered yields from recent highs but the $64,000 question is can we break the 5.00% level on the 10-Year?
- Stocks moved into a one-week winning streak with the S&P 500 rising 1.15% in the last week, ended 10/9.
- U.S. moves into Week 34 of its attack on Iran, seven months.
- The S&P 500 is now on a 3-day losing streak.
- The S&P 500 lost more than -1% for the first time since the end of July. Do we now cluster with more losses in October of greater than -1%?
Key Geopolitical Events of Note
- Economic news of note.
- Weekly – Jobless Claims and Natural Gas Inventories of note.
- Monthly- PPI, Retail Sales, Empire State Manufacturing and the Philadelphia Fed Index of note.
- President Trump’s schedule: (No update as of 7:00 a.m. EDT)
- 8:00 AM: Executive Time (The White House)
- Participates in a lunch at the Rose Garden at 12:30 p.m. EDT.
- Participates in a Policy Meeting at 2:30 p.m. EDT.
- Participates in a Pre-Tape Interview at 4:00 p.m. EDT
- Participates in two Tele-Rallies starting at 6:30 p.m. EDT.
- Fed and Other Speakers of Note:
- Warsh (11:30 p.m. EDT) of note.
- Hammack (4:30 p.m. EDT) of note.
Capital Raises Announced After The Close: With the Government closed yesterday, there were no filings.
- IPO Filings & News: None of note.
- Secondaries Filed Or Priced:
- JSPR: Form S-3.. Up to 284,013,011 Shares of Common Stock.
- Notes Filed Or Priced:
- WTTR – Pricing of Upsized $900 Million of 7.625% Senior Notes Due 2034.
- Convertible Offerings Filed or Priced: None of note.
- Private Placement: None of note.
- Direct Offering: None of note.
- Selling Shareholders:
- SKYX files for 25,250,000 share common stock offering by selling securityholders.
- Mixed Shelf Offerings: None of note.
After The Close:
-
- Earnings After The Close:
- Beat: HOMB +0.01 of note.
- Missed: None of note.
- Dividend Ex Update:
- Thursday: GHC: $1.88 | ABBV: $1.73 | CHCO: $1.00 | AFG: $0.97 | ABT: $0.63 | BFS: $0.59 | CAC: $0.42 | EME: $0.40 | SBR: $0.355 | ALG: $0.34 | TRN: $0.31 | CMTV: $0.26 | FUL: $0.245 | ARR: $0.24 | DAL: $0.215 | BSTZ: $0.1625 | DHY: $0.155 | FCX: $0.15 | VSEC: $0.10 | BCIC: $0.09 | PNNT: $0.08 | BELFB: $0.07 | BELFA: $0.06 | ACA: $0.05 | BHV: $0.0455 | NPB: $0.03
- Friday: WSO: $3.30 | CAT: $1.63 | DEO: $1.20 | EOG: $1.02 | WSM: $0.76 | KWR: $0.53 | MGRC: $0.49 | SNX: $0.48 | CBRL: $0.25 | DCOM: $0.25 | AYI: $0.20 | OXLC: $0.20 | HRZN: $0.09 | JAN: $0.05
- LECO approves a 10% increase in quarterly cash dividend to $0.87 per share.
- VISN declares $1.50 per share special cash distribution.
-
News Of Note:
- RocketLab (RKLB) pushes Neutron inaugural launch target to 2027.
- White House is considering new ways to acquire Bitcoin through federal fund inflows to expand the U.S. Strategic Bitcoin Reserve. (Binance)
- San Francisco Fed President Mary Daly sees further rate hikes as likely but signals no urgency. (Reuters)
- Biggest Movers Up & Down Last Week
- Pops: VISN+2.4%,
- Drops: VNDA -6.4%
- Buybacks:
- SFBS authorizes inaugural stock buyback of up to 2M shares.
- Executive Changes:
- UDR names Blackstone’s Scott McCallum as EVP, chief investment officer.
- SFM CTO James Bahrenburg steps down.
- Earnings After The Close:
What’s Happening This Morning:
Futures S&P 500 -24.50, NASDAQ -368 and Dow Jones +118. Europe is mixed and Asia is lower ex Japan. Bond yield is at 5.089% from 5.20% on the 10-Year. Crude Oil and Brent Crude are mixed with Natural Gas higher. Gold and Silver are higher with Copper lower. The U.S. Dollar is lower versus the Euro, lower against the Pound while lower against the Yen. Bitcoin is at $81,056 from $83,378.
Sector Action: 5 sectors higher and 13 lower.
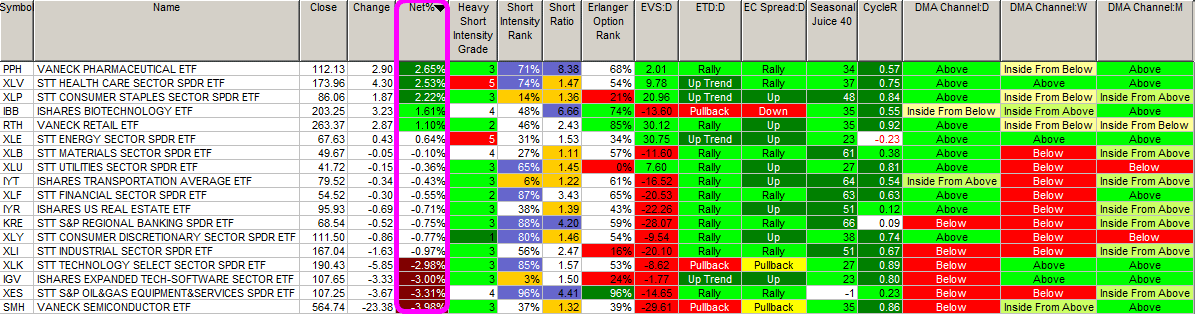
- One-Month Winners: Technology, Utilities, Consumer Cyclical, Consumer Defensive and Communication Services of note.
- Three-Month Winners: Energy, Technology, Materials, Healthcare and Communication Services of note.
- Six-Month Winners: Technology, Energy, Financials, Healthcare and Consumer Defensive of note.
- Twelve-Month Winners: Energy, Technology, Materials, Industrials, Financials and Communication Services of note.
- Year-to-Date Winners: Energy, Technology, Materials, Industrials, Financials and Healthcare of note.
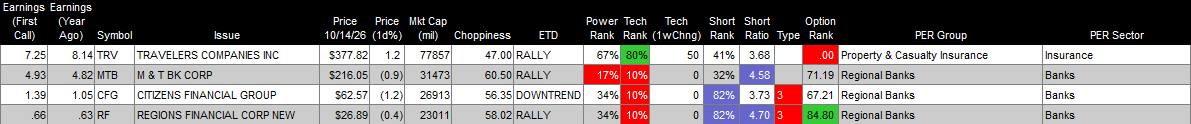
Upcoming Earnings Of Note: (Erlanger Chartroom Software – sorted by market cap, highest to lowest with most visible names)
- Thursday After the Close:
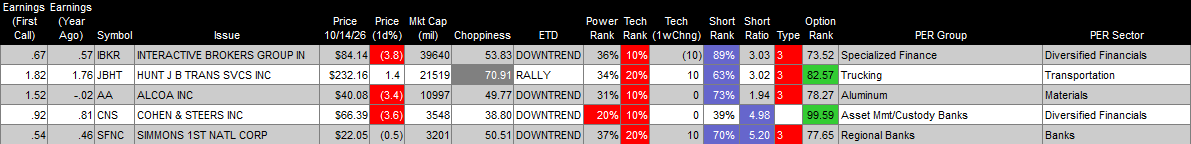
- Friday Before the Open:
Insider Activity: None see Insider Buying with dumb short selling. INBX see Insider Buying with smart short sellers. Above $100,000 in purchases with high shorts but no history: NUAI of note. With the Government closed yesterday, there were no filings.

Notable Earnings of Note This Morning:
- Beat: PNC +0.18, CMC +0.14, TSM +0.14, BNY +0.07, MRSH +0.06, SCHW +0.04, UBS +0.02, FHN +0.01 of note.
- Missed: None of note.
- Flat: MAN of note.
- Still to Report: PLD of note.
Company Earnings Guidance:
- Positive Guidance: ASML of note
- Mixed: None of note.
- Negative or Mixed Guidance: None of note.
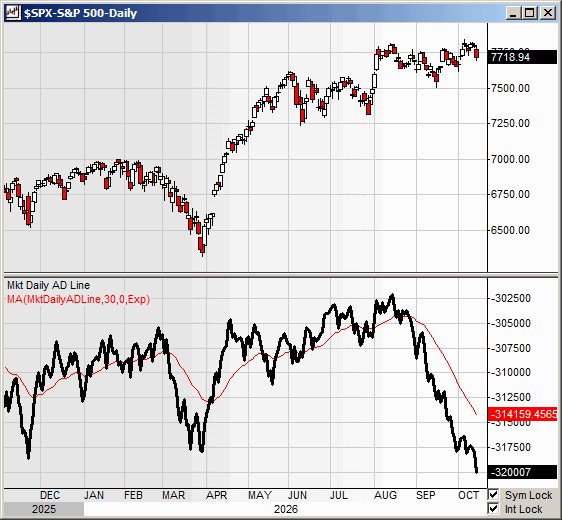
Advance/Decline Line Chart: Bumping along the bottom.
Economic & Geopolitical
- Federal Reserve Speakers of note today:
- Federal Reserve Chairman Warsh speaks at 11:30 p.m. EDT.
- Federal Reserve Cleveland President Hammack speaks at 4:30 p.m. EDT.
- President Trump’s Schedule:
- 8:00 AM: Executive Time (The White House)
- Participates in a lunch at the Rose Garden at 12:30 p.m. EDT.
- Participates in a Policy Meeting at 2:30 p.m. EDT.
- Participates in a Pre-Tape Interview at 4:00 p.m. EDT
- Participates in two Tele-Rallies starting at 6:30 p.m. EDT.
- Economic Data Out –
- Weekly
- Jobless Claims are due out at 8:30 a.m. EDT.
- Natural Gas Inventories are due out at 10:30 a.m. EDT.
- Monthly
- September PPI is due out at 8:30 a.m. EDT and expected to come in at 0.50% from 0.40% in August.
- September Retail Sales is due out at 8:30 a.m. EDT and expected to fall to 0.3% from 1.20%.
- October Empire State Manufacturing Index is due out at 8:30 a.m. EDT and expected to fall to 7.0 from 7.60.
- October Philadelphia Fed Index is due out at 8:30 a.m. EDT and expected to fall to 29 from 37.80.
- Weekly
M&A Activity & Daily: None of note.
Pre-Market Changes:
- Higher: ERIC +12.0%, VISN +5.4%, DXCM +4.1%, VG +3.8%, IBRX +3.1%, AZN +2.4%, SNY +2.2%, WMT +2.2%, TAK +2.1%
- Lower: RKLB -9.3%, CRWV -5.8%, DELL -3.5%, HPE -3.4%, GEV -3.3%, DRS -3.0%, ENS -2.0%, TSM -2.0%
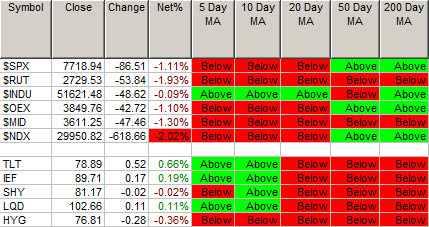
Moving Averages Summary: Stocks are at 69% from 76% above their respective moving averages and Bonds are at 36% from 44%.
Rags & Mags:
-
- France’s presidential candidate Jean-Luc Melenchon vowed to cancel hundreds of billions of France’s national debt and pull out of NATO. (WSJ)
- Far-left France Unbowed leader Jean-Luc Mélenchon unveiled an alternative budget platform pledging to repudiate hundreds of billions of euros in sovereign obligations held by the European Central Bank and withdraw France from NATO’s integrated military command. The radical economic and foreign policy gambit is reigniting investor jitters over French sovereign spreads and European fiscal cohesion as Paris wrestles with mounting deficit pressures.
- A cargo ship sank in the Strait of Hormuz after an air strike. (Bloomberg)
- A commercial container vessel carrying over 2,500 containers sank near the Strait of Hormuz following an explosion, with regional maritime security reporting a strike and Iranian authorities claiming it detonated a naval mine. The incident shatters a brief period of operational calm in the waterway, driving up maritime war-risk insurance premiums and threatening the durability of recent joint escort-assisted crude flows.
- Market Wrap: US Stocks slide continues as AI Rout drives Investors to Bonds. (Bloomberg)
- Global equity futures and major U.S. benchmarks fell sharply as a broad-based valuation unwind in artificial intelligence and semiconductor leaders accelerated, prompting a flight to the safety of sovereign debt. The rotation drove benchmark Treasury yields to multi-week lows as investors sought shelter from tech capital expenditure scrutiny and absorbed sticky core inflation data.
- The U.S. has developed plans to use the “mother of all bombs” to target Iranian nuclear sites and energy infrastructure if President Trump decides to do so before or after the midterms. (CNN)
- Pentagon planners have drafted expanded contingency strike packages that include the potential operational deployment of the 9.7-ton GBU-43/B Massive Ordnance Air Blast (MOAB) against fortified Iranian nuclear facilities and major energy hubs. While the White House maintains that direct military action remains conditional and secondary to diplomatic efforts ahead of the elections, the readiness of deep-penetration options signals heightened brinkmanship across the Persian Gulf.
- Barron’s is + on BUD OSW Q.
- Barron’s highlighted a bullish, cash-flow-driven value thesis across consumer staples, leisure services, and specialized electronics, finding upside in Anheuser-Busch InBev (BUD), cruise health/wellness operator OneSpaWorld Holdings (OSW), and Qnity Electronics (Q). The publication points to resilient balance sheets, steady post-reopening margin expansion, and attractive enterprise valuation multiples as effective counterweights against broader mega-cap tech turbulence.
- France’s presidential candidate Jean-Luc Melenchon vowed to cancel hundreds of billions of France’s national debt and pull out of NATO. (WSJ)
Meeting & Conferences of Note:
- Sellside Conferences:
- H.C. Wainwright Immune Cell Engager Conference
- KeyBanc Private Company Healthcare Conference
- ThinkEquity Small Cap Conference
- U.S. Bancorp Kidney Health Forum
- Wolfe Quantitative & Macro Investment Conference
- Shareholder Meetings: CACI ESTC MDT PAYX of note.
- Top Analyst, Investor: ENGN RGLD SMTC of note.
- Fireside Chat: None of note.
- FDA Presentation: None of note.
- R&D Day: None of note.
- Meetings:
- IMF and World Bank Group Annual Meeting
- Semicon West
- Workday Rising
Upgrades & Downgrades:
The recommendations listed below in this “Upgrade/Downgrade” section are compiled from what we believe are Tier I, II and III firms. Recommendations posted are taken from a variety of sources each day and we only post upgrades or significant initiations as well as downgrades to underweight or sell. The purpose of this posting is to make the reader aware of market-moving recommendations. None of these recommendations should be interpreted as actual recommendations from CAPIS or its employees.
Upgrades: BWA FTRE IONS KMX SMG WMT of note.
Downgrades: DHC of note.