Overnight Summary and Early Morning Trading:
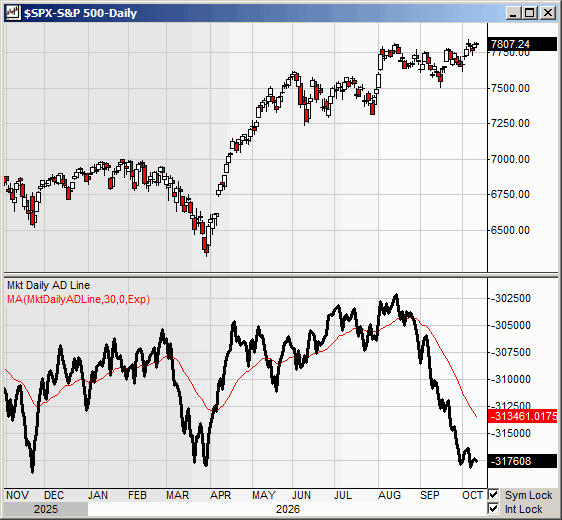
- The S&P 500 finished Monday lower by -0.08% at 7807.24 from Friday higher by 0.59% at 7811.54.
- The S&P 500 sees support now at 7800 from 7700. Resistance is now at 7900 from 7800. In the last five months, support has moved from 6300 to 7800.
- The QQQ (Nasdaq-100 Index ETF) sees support now at 740 from 750. Resistance is now at 750 from 740 as the QQQ closed lower at 746.04.
- Bond Market is higher today on price with the 10-Year Yield at 5.192% from 5.269%.
Executive Summary:
- Bond Markets reopens since being closed on Friday.
- Stocks moved into a one-week winning streak with the S&P 500 rising 1.15% in the last week, ended 10/9.
- U.S. moves into Week 34 of its attack on Iran, seven months.
- The S&P 500 is now on a 1-day losing streak.
Key Geopolitical Events of Note
- Economic news of note.
- Weekly – API Petroleum Institute Data of note.
- Monthly- NFIB Small Business Optimism, Existing Home Sales and the Treasury Budget of note.
- President Trump’s schedule: (No update as of 7:00 a.m. EDT)
- 8:00 AM: Executive Time (The White House · Closed Press)
- Travels to Alaska this morning.
- Delivers speech at 7:30 p.m. EDT in Wasilla, Alaska.
- Fed and Other Speakers of Note:
- Waller (3:45 a.m. EDT), Collins (4:00 p.m.) of note.
Capital Raises Announced After The Close: With the Government closed yesterday, there were no filings.
- IPO Filings & News: None of note.
- Secondaries Filed Or Priced: None of note.
- Notes Filed Or Priced: None of note.
- Convertible Offerings Filed or Priced: None of note.
- Private Placement: None of note.
- Direct Offering: None of note.
- Selling Shareholders: None of note.
- Mixed Shelf Offerings: None of note.
After The Close:
-
- Earnings After The Close:
- Beat: None of note.
- Missed: None of note.
- Dividend Ex Update:
- Tuesday: ACN: $1.71 | ESLT: $1.00 | MVRL: $0.378 | ACM: $0.31 | ACV: $0.22 | UTF: $0.17 | HTD: $0.16 | RNP: $0.14 | PDO: $0.13 | PTY: $0.1188 | RLTY: $0.11 | PCN: $0.11 | PDT: $0.0883 | BNED: $0.08 | PFL: $0.08 | VGI: $0.08 | PFFL: $0.0753 | EDGQ: $0.0708 | ERC: $0.07 | ECC: $0.06 | RCS: $0.04
- Wednesday: GHC: $1.88 | ABBV: $1.73 | MAA: $1.53 | CHCO: $1.00 | ABT: $0.63 | KISB: $0.44 | EME: $0.40 | KAI: $0.36 | BKE: $0.35 | ALG: $0.34 | TRN: $0.31 | FUL: $0.245 | DAL: $0.215 | CSQ: $0.14 | DLY: $0.1167 | DSL: $0.11 | VSEC: $0.10 | VLT: $0.09 | FCX: $0.075 | BELFA: $0.06 | ACA: $0.05
-
News Of Note:
- FormFactor (FORM) and Teradyne (TER) entered a broad technology collaboration focused on next-generation semiconductor test development, validation, and high-volume production. Teradyne agreed to purchase $300 mln of FormFactor common stock as part of the deal.
- Johnson & Johnson (JNJ) TREMFYA shows sustained 3-year remission in Phase 3 Crohn’s studies,
- Applied Materials (MAT) opens $5 bln EPIC semiconductor R&D center with Intel, TSMC, Samsung, Micron, SK hynix partners.
- Kroger (KR) to eliminate roughly 3,000 corporate positions over next three years. (Bloomberg)
- Biggest Movers Up & Down Last Week
- Pops: BMEA +6.6%, NVTS +4.7%, FORM +2.3%.
- Drops: SNDX -16.3%, INCY -3.9%,
- Buybacks: None of note.
- Executive Changes:
- MWA names Michael Morgan CFO, effective after annual report filing.
- NEXN appoints Neil Jones as interim Chair.
- Earnings After The Close:
What’s Happening This Morning:
Futures S&P 500 -8.75, NASDAQ -181.75 and Dow Jones +96. Europe is higher and Asia is mixed. Bond yield is at 5.179% from 5.242% on the 10-Year. Crude Oil and Brent Crude are lower with Natural Gas lower. Gold, Silver and Copper higher. The U.S. Dollar is lower versus the Euro, lower against the Pound while higher against the Yen. Bitcoin is at $83,441 from $82.474.
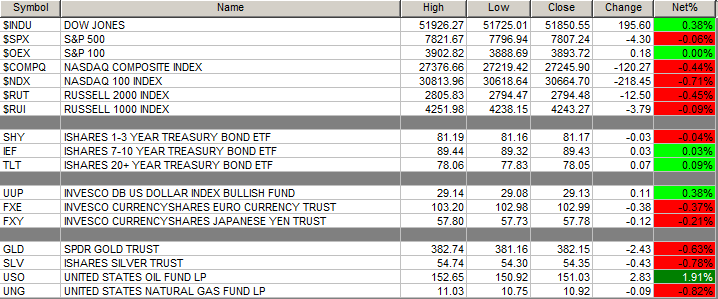
Sector Action: 10 sectors higher and 8 lower.
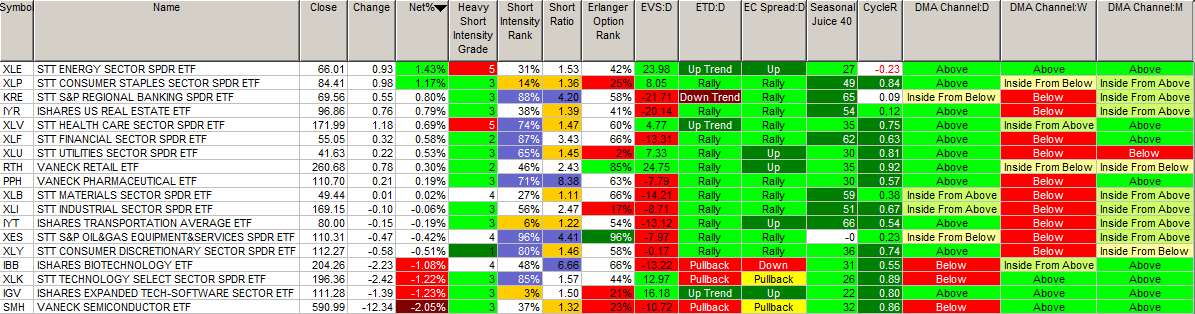
- One-Month Winners: Energy and Communication Services of note.
- Three-Month Winners: Energy, Healthcare and Financials of note.
- Six-Month Winners: Technology, Financials, Healthcare and Energy of note.
- Twelve-Month Winners: Energy, Technology, Materials, Industrials, Financials and Communication Services of note.
- Year-to-Date Winners: Energy, Technology, Materials, Industrials, Financials and Healthcare of note.
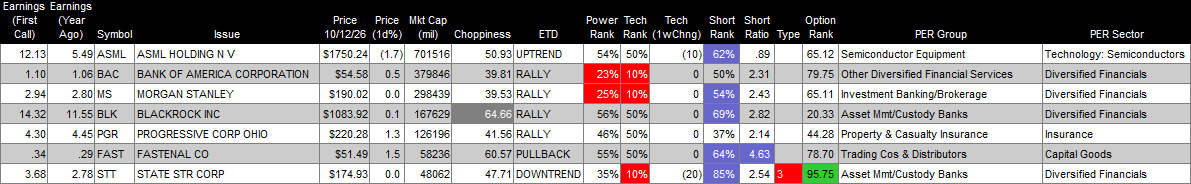
Upcoming Earnings Of Note: (Erlanger Chartroom Software – sorted by market cap, highest to lowest with most visible names)
- Tuesday After the Close:

- Wednesday Before the Open:
Insider Activity: None see Insider Buying with dumb short selling. None see Insider Buying with smart short sellers. Above $100,000 in purchases with high shorts but no history: None of note. With the Government closed yesterday, there were no filings.
Notable Earnings of Note This Morning:
- Beat: GS +4.15, UNH +0.55, DPZ +0.24, JNJ +0.07, ACI +0.03 WFC +0.02 of note.
- Missed: JPM -0.18 of note.
- Flat: None of note.
- Still to Report: C of note.
Company Earnings Guidance:
- Positive Guidance: UNH of note
- Mixed JNJ of note.
- Negative or Mixed Guidance: None of note.
Advance/Decline Line Chart: Bumping along the bottom.
Economic & Geopolitical
- Federal Reserve Speakers of note today:
- Federal Reserve Governor Christopher Waller spoke at 3:45 a.m. EDT.
- Federal Reserve Boston President Susan Collins to speak at 4:00 p.m. EDT.
- President Trump’s Schedule:
- 8:00 AM: Executive Time (The White House · Closed Press) (No update as of 7:00 a.m. EDT)
- Travels to Alaska this morning.
- Delivers speech at 7:30 p.m. EDT in Wasilla, Alaska.
- Economic Data Out –
- Weekly
- API Petroleum Institute Data is due out at 4:30 p.m. EDT.
- Monthly
- September NFIB Small Business Optimism was out at 6:00 a.m. EDT and came in at from 98.70.
- September Existing Home Sales are due out at 10:00 a.m. EDT and expected to come in at 3.96 million from 3.98 million in August.
- September Treasury Budget is due out at 2:00 p.m. EDT and came in last month at $-166.8 billion.
- Weekly
M&A Activity & Daily: None of note.
Pre-Market Changes:
- Higher: BMEA +6.6%, EFXT +4.3%, NRIX +3.5%, TSEM +3.1%, NVTS +2.2%
- Lower: SNDX -16.4%, SKHY -5.1%, SNDK -3.9%, MU -3.1%, MWA -2.8%, DPZ -2.8%, CRDO -2.4%, AMAT -2.0%, BE -2.0%, AVBP -2.0%, FSM -2.0%
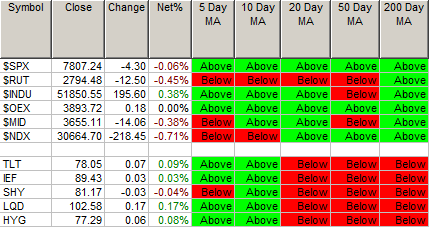
Moving Averages Summary: Stocks are at 69% from 76% above their respective moving averages and Bonds are at 36% from 44%.
Rags & Mags:
-
- JP Morgan and Wells Fargo miss expectations. (WSJ)
- Both JPMorgan Chase (JPM) and Wells Fargo (WFC) kicked off third-quarter bank earnings with top-line shortfalls as higher deposit costs and muted lending activity pinched net interest income. While Wells Fargo managed a modest EPS beat, JPMorgan missed on both revenue and earnings per share, setting a cautious tone for large-cap financial margins. The results, reported across coverage on the Chartmill Earnings Feed and the StockStory Analysis Desk, pressured both tickers in pre-market action.
- The Forces Driving Up Bond Yields Take a Troubling Turn. (NYT)
- Long-term Treasury yields are breaking higher, driven no longer by robust economic expansion optimism, but by mounting term premiums, sticky inflation, and growing market unease over sovereign debt issuance. Bond investors are demanding steeper compensation to absorb prolonged fiscal deficits against sticky crude prices. The shift represents a more destabilizing tightening of broader financial conditions that threatens equity valuations and corporate borrowing channels alike.
- Goldman Equity Traders Top Estimates as Fixed Income Falls Short. (Bloomberg)
- Goldman Sachs (GS) delivered a split third-quarter trading performance, with equities trading desk revenue surging on heavy retail and institutional volume to offset notable cooling in fixed income, currencies, and commodities (FICC). The trading divergence highlights shifting desk dynamics on Wall Street, as detailed in the TradingKey Q3 Earnings Report, where rising non-compensation expenses are putting fresh scrutiny on operating leverage.
- Market Wrap: Chip Selloff rolls on as big bank earnings begin. (Bloomberg)
- Semiconductor equities extended their weekly slide as supply constraints and valuation resets dragged on mega-cap tech, casting a shadow over early third-quarter bank earnings results. Investors showed limited appetite to bid up early financial beats against rising benchmark yields, leaving major equity benchmarks defensive into the opening bell.
- Federal Reserve Chicago President Austan Goolsbee notes inflation is too high still, also notes that tariffs and oil can lead to stagflation.
- Federal Reserve Bank of Chicago President Austan Goolsbee cautioned that price pressures remain uncomfortably elevated above the central bank’s 2% target, warning that compounding supply shocks could complicate policy. He emphasized that a confluence of rising import tariffs and volatile energy costs threatens to push the economy into a stagflationary environment, creating a difficult trade-off between dampening inflation and preserving labor market stability, as detailed in macro coverage by BNN Bloomberg and Fox Business.
- JP Morgan and Wells Fargo miss expectations. (WSJ)
Meeting & Conferences of Note:
- Sellside Conferences:
- Canaccord Biotech Private Company Symposium
- Maxim Growth Summit
- Needham Private Company Conference – Biotech and MedTech
- Wolfe Quantitative & Macro Investment Conference
- Shareholder Meetings: PG USAU of note.
- Top Analyst, Investor: ALEC, AMAT, BGC, ACIC, KURA, WDAY of note.
- Fireside Chat: None of note.
- FDA Presentation: None of note.
- R&D Day: None of note.
- Meetings:
- CEO Investor Summit
- IMF and World Bank Group Annual Meeting
- Semicon West
- Workday Rising
Upgrades & Downgrades:
The recommendations listed below in this “Upgrade/Downgrade” section are compiled from what we believe are Tier I, II and III firms. Recommendations posted are taken from a variety of sources each day and we only post upgrades or significant initiations as well as downgrades to underweight or sell. The purpose of this posting is to make the reader aware of market-moving recommendations. None of these recommendations should be interpreted as actual recommendations from CAPIS or its employees.
Upgrades: VFC of note.
Downgrades: PSUS of note.